
Kerala High Court
DRAT Need Not Mandate 50% Of Debt Due As Pre-Deposit To Entertain Appeals, Must Consider Subject Matter: Kerala High Court
The Kerala High Court recently held that there is no mandate under law that the pre-deposit amount should always be 50% of the debt due, while entertaining appeals under Section 18 SARFAESI [Securitisation and Reconstruction of Financial Assets and Enforcement of Security Interest] Act, challenging the order of the Debts Recovery Tribunal.It clarified that the Debt Recovery Appellate Tribunal (DRAT), while determining the amount to be deposited, shall take into consideration the subject matter...
Arbitration Agreement Is Valid Even Without Signature If Parties Acted Upon It: Kerala High Court
The Kerala High Court held that written agreement need not to be signed by the parties if the consensus ad idem and intention to arbitrate is reflected from the conduct of the parties and documentary evidence. Justice S. Manu allowed the application seeking reference to arbitration holding that an arbitration agreement in writing may exist even without signatures provided there is a clear evidence that both parties acted upon it. Sigmatic Nidhi Ltd had advanced loans to the...
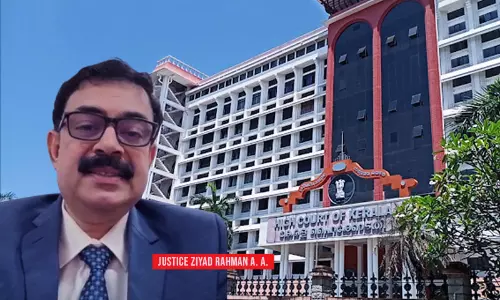
Disclosure Of Income & Payment Of Income Tax Do Not Bar Proceedings Under Benami Transactions Act: Kerala High Court
The Kerala High Court has held that disclosure of income and payment of tax under the Income Tax Act, 1961, does not preclude initiation of proceedings under the Prohibition of Benami Property Transactions Act, 1988. Justice Ziyad Rahman A.A. agreed with the department that the fact that the assessees have disclosed the income in the return and the same was proceeded against under the provisions of the Income Tax Act, by itself, cannot be a reason to interfere with the proceedings...
Kerala High Court Quashes Income Tax Appellate Order Against AMMA, Directs Fresh Consideration
The Kerala High Court has set aside an order passed by the Commissioner of Income tax (Appeals), against the Association of Malayalam Movie Artists (AMMA), holding that the appellate authority failed to comply with the mandatory requirements under the Income Tax Act.Justice Ziyad Rahman A A, observed that the Commissioner of Income Tax (Appeals) erred by rejecting AMMA's appeal solely on the ground of non-appearance, without addressing the merits of the case as mandated under Section 250(6) of...
Income Tax Act | Revisional Power U/S 263 Cannot Be Invoked When AO Allows Deduction U/S 32AC After Proper Inquiry: Kerala High Court
The Kerala High Court stated that revisional power under Section 263 of the Income Tax Act cannot be invoked when Assessing Officer (AO) allowed deduction under Section 32AC after proper inquiry. Justices A. Muhamed Mustaque and Harisankar V. Menon opined that merely for the reason that AO extended the deduction claimed after carrying out investigations, the exercise of the power under Section 263 of the Act is not required. At worst, the revisional authority can correct the error, if...
GST Levy On Group Health Insurance Policies Challenged; Kerala High Court Grants Interim Relief To Union Bank Pensioners
The Kerala High Court has granted interim relief to retired employees of the Union Bank by allowing them to renew their group health insurance policies without paying the 18% Goods and Services Tax (GST) on the premium.The Court passed the interim order in a writ petition filed by Vinod Mukundan and others, including the All India Union Bank Pensioners & Retirees Federation, challenging the levy of 18% GST on group health insurance policies. While the GST levy on individual health...
S.263 Income Tax Act Can Be Invoked When AO Fails To Address Core Issue In Assessment Order: Kerala High Court
The Kerala High Court held that Section 263 of the Income Tax Act, 1961, can be invoked where the Assessing Officer (AO) fails to address a core issue in the assessment order. The bench opined that the main issue does not appear to have been addressed by the assessing authority while issuing an order under Section 143(3) of the Act. Since the assessment order does not appear to have addressed the issue with reference to the competing provisions, exercise of the power under Section 263...
S.36(1)(vii) Income Tax Act | Closing Individual Debtor Accounts Not Mandatory For Bad Debt Deduction: Kerala High Court
The Kerala High Court stated that closing individual debtor accounts is not mandatory for bad debt deduction under Section 36(1)(vii) of the Income Tax Act, 1961. Section 36(1)(vii) of the Income Tax Act, 1961, deals with the deduction of bad debts. It allows the taxpayer to claim a deduction for bad debts that have been written off in the books of accounts during the previous financial year. Justices A. Muhamed Mustaque and Harisankar V. Menon, after referring to the case of...
Change In Form Or Rephrasing Of Relief Cannot Defeat Principle Of Constructive Res Judicata: Kerala High Court
The Kerala High Court has recently clarified that changing the form or rephrasing of a relief prayed for cannot defeat the principles of res judicata and constructive res judicata.Justice Mohammed Nias C.P. was considering a writ petition filed by a registered MSME (Micro, Small and Media Enterprise) that had sought protection under the Central Government notification, which mandates banks and financial institutions to refer stressed MSME accounts for corrective measures.According to the...
Limitation Under Rule 68B Of Income Tax Act Does Not Apply To RDDB Act Proceedings: Kerala High Court
The Kerala High Court held that the limitation under Rule 68B of the second schedule to the Income Tax Act does not apply to RDDB Act (Recovery of Debts Due to Banks and Financial Institutions Act, 1993) proceedings. Justice Mohammed Nias C.P. stated that Rule 68B of the Second Schedule to the Income Tax Act, 1961, has no mandatory application to recovery proceedings under the RDDB Act. It is also relevant that under Sections 19(22) and 25 of the RDDB Act, the Recovery Officer derives...
Income Tax Act | Non-Production Of Form 3CL Isn't Material Suppression; Not Grounds To Reopen Assessment U/S 147: Kerala High Court
The Kerala High Court held that the non-production of Form 3CL is not material suppression and is not a valid ground to reopen the assessment under Section 147 of the Income Tax Act. Under Section 35(2AB) of the Income Tax Act, 1961, any expenditure on scientific research is allowable as a deduction. A sum equal to one and one-half times the expenditure is allowed as such a deduction. Section 147 of the Income Tax Act, 1961, empowers the Assessing Officer (AO) to reassess or...