
Kerala High Court
CGST | Dept Must First Proceed Against Supplier Before Issuing Show Cause To Recipient For ITC Mismatch: Kerala High Court
The Kerala High Court has held that the department cannot proceed against a recipient for ITC mismatch without first initiating proceedings against the supplier. Section 42(3) of the Central Goods and Services Tax (CGST) Act, 2017, deals with the communication of discrepancies in Input Tax Credit (ITC) claims between the recipient and the supplier. Justice Ziyad Rahman A.A. observed that no proceedings had been initiated against the suppliers before the issuance of notice under...
Revisional Power U/S 263 Income Tax Act Cannot Be Upheld By Tribunal On Grounds Not Taken By Commissioner: Kerala High Court
The Kerala High Court has held that a tribunal cannot travel beyond the grounds not cited by the commissioner while exercising jurisdiction under Section 263 Income Tax Act.Justices A. Muhamed Mustaque and Harisankar V. Menon stated that only one reason was highlighted by the Commissioner for exercising the power under Section 263 of the Act and the Tribunal having found the said reason as not a valid one, the Tribunal should have stopped there rather than making further observations as regards...
Kerala High Court Grants Interim Protection To 'Bokashi Bucket' Mark, Bars Sale Of Identical Compost Bins
The Kerala High Court has put a temporary restraint on a Kozhikode-based business from making or selling compost bins using the name “Bokashi Bucket,” after finding that the term is a registered trademark owned by Global Pharmaceuticals. A single bench of Justice S Manu passed the order on November 18, 2025, overturning a Additional District Court order refusing to grant protection to the company.Global Pharma told the court that “Bokashi Bucket” is both its registered trademark and part of a...
Single Partner In A Firm Cannot Invoke Arbitration Without Explicit Authority From Other Partners: Kerala High Court
The Kerala High Court has held that one partner of a partnership firm cannot, without explicit authorisation from the other partners, invoke an arbitration clause or seek appointment of an arbitrator under Section 11 of the Arbitration and Conciliation Act, 1996.Justice S. Manu, delivered the judgment in an arbitration request.The arbitration request was filed by a partner of M/s P K Chandrasekharan Nair and Co., a partnership firm, which was operating a retail outlet of petroleum products of...
Income Tax Act | SBI Not 'Assessee In Default' U/S 201 For Not Deducting TDS While Obeying Court's Interim Order: Kerala High Court
The Kerala High Court has held that the State Bank of India (SBI) cannot be treated as an 'assessee in default' under Section 201 of the Income Tax Act for not deducting Tax Deducted at Source (TDS) on Leave Travel Concession (LTC) payments, as it was bound by an interim order which prohibited such deduction. Justices A. Muhamed Mustaque and Harisankar V. Menon examined whether the SBI, having been restrained by an interim order of the High Court from deducting TDS, could be held to be...
Assessee Missed Hearing Due To Faulty VC Link & Hearing Email Sent At 3AM: Kerala High Court Quashes CIT(A) Order
The Kerala High Court has set aside an order passed by the Commissioner of Income Tax (Appeals) after finding that the assessee missed the hearing due to the non-functional video-conference link (VC link) and because the hearing link was emailed at an odd hour, i.e., at 3:13 a.m. CDT (Central Daylight Time) while he was in the U.S. Justice Ziyad Rahman A.A. stated that the assessee could not utilise the opportunities for reasons beyond his control. Therefore, the assessee can be...
Affidavit Of Cost Accountant In Personal Hearing Cannot Be Ignored When Facts Are Admitted By State Tax Officer: Kerala High Court
The Kerala High Court has held that an affidavit by professionals, such as a cost accountant, given during a personal hearing, cannot be ignored, especially when a state tax officer admits facts referred therein. Justice Ziyad Rahman A.A. stated that when a professional swears an affidavit before this Court, highlighting the matters that transpired during the course of the hearing, the same cannot be simply ignored, particularly in a situation where, to some extent, there is an...
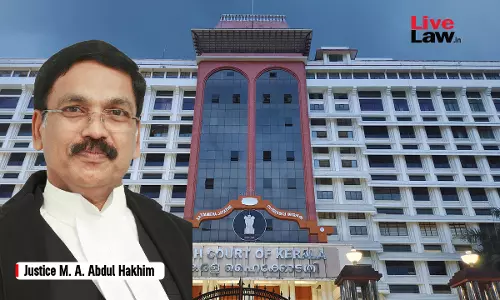
KVAT Act | Permission For Compounding Tax Cannot Be Cancelled For Suppression; Only Suppressed Turnover Can Be Taxed: Kerala High Court
The Kerala High Court has held that under the KVAT Act (Kerala Value Added Tax Act, 2003), the assessing authority cannot cancel permission to pay tax at compounding rates for suppression in the same year it was opted, and only the suppressed turnover can be taxed at normal rates. Justice M.A. Abdul Hakhim opined that cancellation proceedings are still pending, and the cancellation is not carried out, and the assessment is not concluded on a best judgment assessment basis. In such a...
Cancelled GST Registration Cannot Be Restored Solely To Claim ITC Benefit U/S 16(6) CGST Act: Kerala High Court
The Kerala High Court has held that a cancelled GST registration cannot be restored solely to claim the ITC (Input Tax Credit) benefit under Section 16(6) CGST Act (Central Goods and Services Tax Act, 2017). Section 16(6) of the Central Goods and Services Tax Act, 2017, enables the taxpayer to claim the input tax credit available in the ledger, in case the order cancelling the registration is revoked by any order, either under Section 30 or pursuant to any order made by the appellate...
Contractor Can Claim Increased GST During Work, Even If Bills Were Paid Before Rates Increased: Kerala High Court
The Kerala High Court has held that a contractor can claim increased GST (Goods and Services Tax) during work, even if bills were paid before the rate increase. Justice Ziyad Rahman A.A. opined that at the time of execution of the contract, the rate was only 5% and the increase took place during the execution of the work. Thus, the assessee is entitled to a differential amount of tax. In this case, the assessee/petitioner is a partnership firm and is engaged in the construction...
Kerala High Court Directs GST Department To Ensure No Tax Evasion In Frozen Chicken Sale
Disposing of a writ petition alleging that frozen chicken was being sold at 0% GST instead of the applicable 5%, the Kerala High Court recently directed the GST department to ensure that no tax evasion takes place. Justice Ziyad Rahman A.A. also noted that the State GST Department was already investigating the matter. Hence, the Court disposed of the writ petition filed by the petitioner, who is a chicken meat dealer, who alleged that tax evasion was taking place in the sale of...
Income Tax Act | Co-operative Societies Not Engaged In Banking Not Entitled To TDS Exemption U/S 194A(3)(iii): Kerala High Court
The Kerala High Court has held that co-operative societies not engaged in banking are not entitled to TDS (Tax Deducted at Source) exemption under section 194A (3)(iii) of the Income Tax Act. Section 194A(3) of the Income Tax Act, 1961 provides exemptions from TDS on interest for certain persons or institutions. Justice Ziyad Rahman A.A. was dealing with a petition challenging the Constitutional validity of the proviso to section 194A(3) of the Income Tax Act, 1961, which imposed...