
Gujarat High Court
Gujarat High Court Upholds Validity Of GST Advisory On Interest For Delayed Tax Payment
The Gujarat High Court has upheld the validity of the GST advisory on interest for delayed tax payment. Justices Bhargav D. Karia and Pranav Trivedi stated that the reference to Section 79 of the GST Act in the advisory is only to put the assessee on guard as to such outstanding liability as per the record of the Authority so that the assessee can either make the payment of such liability if agreed or may oppose the same when the notice in Form GST DRC-01D is received by the assessee...
DTAA Prevails Over S.206AA Of Income Tax Act For TDS On Payments To Non-Residents Without PAN: Gujarat High Court
The Gujarat High Court stated that DTAA (Double Taxation Avoidance Agreement) prevails over Section 206AA of Income Tax Act for TDS on payments to non-residents without PAN. Justices Bhargav D. Karia and Pranav Trivedi was addressing the appeals pertains to alleged short deduction of TDS and raising demand by invoking provisions of section 206AA of the Income Tax Act, 1961. Section 206AA of Income Tax Act, 1961 requires every taxpayer who receives taxable income to furnish their...
State Tax Authorities Not Mandated To Issue DIN With Orders Or Summons: Gujarat High Court
The Gujarat High Court stated that state tax authorities not mandated to issue din with orders or summons. The Division Bench of Justices Bhargav D. Karia andP.M. Ravalobserved that “there is no mechanism of issuance of DIN on any of the communication, notice, summons, orders issued by the State Tax Authorities. In such circumstances, the contention raised on behalf of the assessee, that the DIN is not mentioned in any of the summons and the previously attachment order being without...
When Court Lacks Jurisdiction To Entertain Application U/S 34 Of Arbitration Act, It Cannot Set Aside Award On Merits: Gujarat High Court
The Gujarat High Court bench of Chief Justice Sunita Agarwal and Justice D.N. Ray and has held that Once the Court lacked jurisdiction to entertain the Section 34 application—having been filed beyond the limitation prescribed under Section 34(3) and its proviso—any finding on the validity of the arbitral award as void ab initio was without legal authority. Entertaining a time-barred application under Section 34 was a grave error of law on the part of the learned Court. Brief Facts: ...
Omission Of Rule 96(10) Of CGST Rules Operates Prospectively But Applies To All Pending Proceedings: Gujarat High Court
The Gujarat High Court stated that omission of Rule 96(10) Of CGST Rules, 2017 operates prospectively but applies to all pending proceedings. The Division Bench of Justices Bhargav D. Karia and D.N. Ray was addressing the issue where a group of petitions have challenged the vires of Rule 96(10) of the Central/State Goods and Services Tax Rules, 2017 as substituted by the Central Goods and Services Tax (12th Amendment) Rules, 2018 with effect from 9.10.2018. The ...
Whether Compensation Cess Is Leviable On Goods Supplied To Merchant Exporter: Gujarat High Court Asks GST Council To Decide
The Gujarat High Court has referred a matter to the GST Council to decide on whether the compensation cess is leviable on goods supplied to merchant exporter. The Division Bench of Justices Bhargav D. Karia and D.N. Ray observed that “……..no notification is issued by the Central Government or State Government under the Compensation Cess Act and therefore, the assessee is made liable to pay Compensation Cess at normal rate i.e. 160% on the supply of goods to merchant exporters for...
Penalty Orders U/S 270A Of Income Tax Act Cannot Be Issued After Approval Of Resolution Plan U/S 31 Of IBC: Gujarat HC
The Gujarat High Court bench of Justices Bhargav D. Karia and D.N.Ray has held that Penalty orders under Sections 270A, 271(1)(c), and 271AAC(1) of the Income Tax Act, 1961 (Income Tax Act) cannot be issued after the approval of the Resolution Plan under Section 31 of the Insolvency and Bankruptcy Code, 2016 (Code). Once the Resolution Plan is approved by the Adjudicating Authority, all claims, including statutory dues, stand extinguished, and no further proceedings in respect of such dues...
Notice U/S 263 Of Income Tax Act Cannot Be Issued By Authority After Approval Of Resolution Plan U/S 31 Of IBC: Gujarat High Court
The Gujarat High Court bench of Justice Bhargav D. Karia and Justice D.N.Ray has held that after approval of the Resolution Plan under Section 31 of the Insolvency and Bankruptcy Code, 2016 (Code), all liabilities prior to the approval of the plan stand extinguished. Therefore, the Income Tax Authority cannot be permitted to issue a notice under Section 263 of the Income Tax Act, 1961 (Act) seeking to revise the assessment after the approval of the Plan. Brief Facts: Amw Auto...
Assessee Entitled To Interest On Refund Under Direct Tax 'Vivad Se Vishwas' Scheme: Gujarat High Court
The Gujarat High Court stated that the assessee is entitled to the interest on refund under Direct Tax Vivad Se Vishwas Scheme. “it is true that the assessee is not entitled to interest under Section 244A of the Income Tax Act, 1961, however, when the assessee has opted for direct tax for Vivad se Visvas Scheme 2020 and filed the application which was approved by the designated authority and refund order is also passed as per the said scheme on 12/05/2022 by the Jurisdictional...
Plea That Signed Copy Of Award Was Not Received Cannot Be Raised For First Time In Appeal U/S 37 Of Arbitration Act: Gujarat High Court
The Gujarat High Court bench of Chief Justice Sunita Agarwal and Justice Pranav Trivedi has held that the plea that limitation period for challenging the award under section 34 of the Arbitration and Conciliation Act, 1996 (Arbitration Act) did not start as the signed copy of the award was not received by the party, cannot be raised for the first time in appeal under section 37 of the Arbitration Act. Brief Facts: The present appeals have been filed against orders passed by the Civil...
Subsidiary Supplying To Parent Company In Independent Capacity Cannot Be Considered 'Intermediary Service' U/S 2(13) IGST Act: Gujarat HC
The Gujarat High Court has made it clear that where a subsidiary company provides goods or services to its parent company in its independent capacity, it cannot be said that such services fall under 'intermediary service' under Section 2(13) of the Integrated Goods and Service Tax Act, 2017. The provision defines “intermediary” as a broker, an agent or any other person who arranges or facilitates the supply of goods or services or both, between two or more persons. In the case at...
Court's Jurisdiction U/S 34 Of Arbitration Act Against Award Under MSMED Act Is Determined By Agreement Between Parties: Gujarat HC
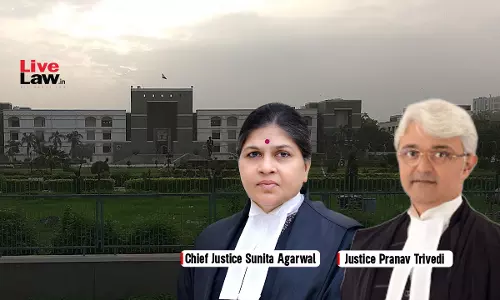
The Gujarat High Court bench of Mrs. Chief Justice Sunita Agarwal and Mr.Justice Pranav Trivedi of has held that the jurisdiction of the Court to hear the application under Section 34 of the Arbitration Act' 1996 as to challenge the award passed under Section 18(4) of the MSMED Act' 2006, would be governed by the agreement between the parties which has conferred exclusive jurisdiction to a particular Court. Brief Facts The present appeal is directed against the judgment and order...