
SERVICE TAX

CESTAT Chandigarh Sets Aside ₹2.39 Crore Service Tax Demand Against SBI Card
The Customs, Excise, and Service Tax Appellate Tribunal (CESTAT), Chandigarh, has set aside a ₹2.39 crore service tax demand against SBI Card and Payment Services Ltd., holding that a show cause notice (SCN) that fails to identify the taxable service, the service recipient or the consideration cannot sustain such a demand. The tribunal observed, "We find that the SCN does not specify as to what was the service rendered by the appellants and to whom and what was the consideration thereon."A bench...
COVID Limitation Extension Can't Revive Time-Barred Service Tax Demands: CESTAT Kolkata
The Customs, Excise, and Service Tax Appellate Tribunal (CESTAT), Kolkata, has ruled that the COVID-19-related extension of limitation cannot revive tax demands that had already become time-barred under the statute. A coram of Judicial Member R. Muralidhar and Technical Member K. Anpazhakan observed, "The subsequent exclusion of limitation during the pandemic cannot revive a cause of action or breathe life into a demand which had already become time-barred under the statute. The law relating to...
Financial Crisis Reasonable Cause To Waive Service Tax Penalty: Madras High Court
The Madras High Court on 27 July held that penalties under the Finance Act, 1994 cannot be imposed where a taxpayer proves a genuine financial crisis as a reasonable cause for delayed payment of service tax, ruling that a Tribunal's finding of financial incapacity based on material on record cannot be interfered with in appeal. A Division Bench of Justices G. Jayachandran and N. Mala dismissed two appeals filed by the GST and Central Excise Department against the CESTAT order that waived...
Labour Contractor Liable For Service Tax Despite Production-Based Payments: CESTAT New Delhi
The New Delhi Customs, Excise and Service Tax Appellate Tribunal (CESTAT) on 31 July held that a labour contractor providing workers to a steel company was liable to pay service tax as the agreement was a manpower supply contract and not a job work arrangement for manufacturing. A Bench of Judicial Member Binu Tamta and Technical Member P.V. Subba Rao dismissed the appeal filed by Padam Charan Guman Singh and upheld the demand of service tax, interest and penalty under Section 78 of the Finance...
Refund Of Service Tax Cannot Be Decided Before Determining Nature Of Contract: Kerala High Court
The Kerala High Court on 27 July held that the question of refund or adjustment of Service Tax cannot be decided before the Assessing Authority determines whether the underlying contract is a works contract or a service contract, as the nature of the contract determines the applicable tax liability. A Division Bench of Justices Devan Ramachandran and Basant Balaji partly allowed the appeals filed by Gaiagen Technologies Private Limited (formerly Pest Control India Private Limited) and set aside...

Skoda's Technical Know-How Licence To Indian Unit Not Consulting Engineer Service: CESTAT Mumbai
The Mumbai Bench of the Customs, Excise, and Service Tax Appellate tribunal (CESTAT) has held that Skoda Auto Volkswagen India Pvt. Ltd.'s licence to use technical know-how, technical documentation, and trademarks from its Czech parent company did not amount to a "Consulting Engineer Service" under the Finance Act, 1994. The bench observed that the arrangement was merely a licence to use pre-existing intellectual property and not a contract for engineering advice or consultancy.Judicial Member...

LIC Not Liable To Pay Service Tax On Premiums Retained After Policy Lapse: CESTAT Mumbai
The Mumbai Bench of the Customs, Excise and Service Tax Appellate Tribunal (CESTAT) has ruled that the Life Insurance Corporation of India (LIC) is not liable to pay service tax on premiums retained after insurance policies lapse or are repudiated. It held that retaining such amounts does not amount to a taxable service of "agreeing to tolerate an act" under Section 66E(e) of the Finance Act, 1994.A coram of Judicial Member S.K. Mohanty and Technical Member M.M. Parthiban observed that there was...

Coal Beneficiation Not Taxable As Business Auxiliary Service Before June 1, 2007: CESTAT Delhi
The Customs, Excise and Service Tax Appellate Tribunal (CESTAT), New Delhi has recently held that beneficiation and washing of coal could not be taxed under the category of Business Auxiliary Service for the period prior to June 1, 2007. Relying on an earlier case involving the taxpayer beore it, the tribunal ruled, "In that circumstance, reliance has been placed in appellant's own case for the earlier case(supra), we hold that the activity of beneficiation/ washing of coal does not fall under...
NBFC's VCF Investment Profits Not Service Taxable Though Clubbed With Management Fees: CESTAT Kolkata
The Kolkata Bench of the Customs, Excise and Service Tax Appellate Tribunal (CESTAT) recently reiterated that the nomenclature used in an assessee's books of account cannot determine whether a transaction is liable to service tax.Holding that the Revenue had failed to establish that profits earned by an NBFC from investing in a Venture Capital Fund were consideration for a taxable service, the bench observed, "The revenue has relied upon the accounting nomenclature to confirm the demand on the...
CA-CPT, ICWA Foundation Coaching Eligible For Service Tax Exemption: CESTAT Hyderabad
The Customs, Excise and Service Tax Appellate Tribunal (CESTAT), Hyderabad has held that coaching imparted for CA-CPT, ICWA Foundation and Intermediate (10+2) examinations is exempt from service tax under the 2011 exemption notification. It held that these courses lead to educational qualifications recognised by law and that the notification does not confine the benefit to the final stage of an educational programme.A coram of Judicial Member Angad Prasad and Technical Member P. Anjani Kumar...
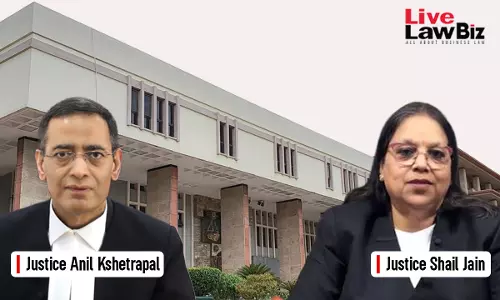
Revenue's Appeal Against CESTAT's Service Taxability Ruling Lies Before Supreme Court: Delhi High Court
The Delhi High Court has held that an appeal against a CESTAT order determining the taxability of a particular service is not maintainable before the High Court and must instead be filed before the Supreme Court under Section 35L of the Central Excise Act, 1944.A Division Bench of Justices Anil Kshetarpal and Shail Jain relied on Commissioner of CGST and Central Excise, Delhi South v. M/s Spicejet Ltd., SERTA 2/2024 to conclude,“where the CESTAT determines the taxability of a particular service,...

CESTAT Hyderabad Quashes Service Tax Demand On UltraTech Over Railway Wagon Freight Concession
The Hyderabad Bench of the Customs, Excise and Service Tax Appellate Tribunal (CESTAT) has held that the freight concession granted by the Indian Railways under the Liberalized Wagon Investment Scheme (LWIS) is a policy incentive and not consideration for any taxable service.A coram of Judicial Member Justice Angad Prasad and Technical Member P. Anjani Kumar, giving relief to UltraTech Cement observed,"We hold that the appellant has not rendered any taxable service to the Indian Railways under...