
Audit Objection Can't Reopen Scrutiny-Completed Assessment Without Fresh Material: Gujarat High Court
Arvind Kumar Tiwari
24 Sept 2026 4:44 PM IST
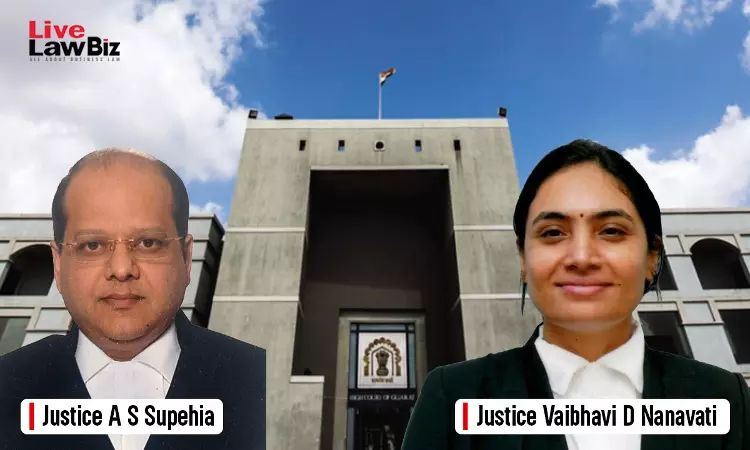
The Gujarat High Court on 17 September held that an assessment cannot be reopened merely on the basis of an audit objection when the underlying issue was examined during the original scrutiny and no fresh or tangible material indicates escapement of income.
A Division Bench comprising Justices A.S. Supehia and Vaibhavi D. Nanavati quashed the Section 148A(3) order and consequential Section 148 notice issued to Lodestone Software Services Pvt. Ltd. for Assessment Year 2022-23, finding that the reopening was based on a misreading of the audit report. The judges held:
“...we are of the considered opinion that the impugned order as well as show-cause notice are required to be quashed and set aside for non-application of mind by the respondent-authority, and also for the reason that the reopening is nothing but a change of opinion since all the materials were available with the Assessing Officer at the time of original scrutiny proceedings and there is no fresh or tangible material available with the Assessing Officer to reopen the assessment, which could suggest that the income chargeable to tax has escaped assessment.”
Lodestone Software Services had filed its return declaring total income of Rs. 32.13 crore. During scrutiny, the Assessing Officer sought reconciliation of expenses with TDS deducted and paid, along with details of disallowances under Section 43B of the Income Tax Act.
The company furnished the required information, including details of TDS amounting to Rs. 17.80 crore on salary payments. The assessment was thereafter completed under Section 143(3), accepting the returned income.
An audit objection was subsequently raised alleging that Rs. 17.54 crore of TDS had been incorrectly claimed as a deduction under Section 43B. During the Section 148A proceedings, the company explained that it had not claimed the amount as an expenditure or deduction in its return.
The Court examined the income tax return and audit report and found that the only deduction under Section 43B actually claimed was Rs. 51.94 lakh towards leave encashment.
It noted that the Assessing Officer had already examined the relevant TDS details during the original scrutiny, including the reconciliation of expenses with TDS and the computation of disallowances under Section 43B. Since the company had furnished the relevant information and the assessment was completed after examining the material, it found no fresh material to support a belief that taxable income had escaped assessment.
Further, the Bench found that the alleged Rs. 17.54 crore deduction represented TDS on salary, contractor, consultancy and professional-fee payments. The amount had been wrongly treated as a deduction under Section 43B due to a misreading of the audit report.
As the TDS issue had already been examined during the original scrutiny and the relevant material had been disclosed, the judges held that the subsequent reopening amounted to a change of opinion and was not based on any new or tangible material.
Accordingly, the High Court allowed the writ petition and quashed the show-cause notice and consequential order under Section 148A.
Counsel for the Petitioner: Sangeeta Pahwa, for Thakkar and Pahwa Advocates
Counsel for Respondent No. 2: Dev D. Patel
Counsel for Respondent No. 1: Pradip D. Bhate