Bombay High Court Quashes Reassessment Against Defunct Company's PAN After Conversion Into LLP
Rajnandini Dutta
6 Nov 2026 7:22 PM IST
The Bombay High Court has quashed income tax reassessment proceedings initiated against the PAN of a company that had ceased to exist after its conversion into a Limited Liability Partnership (LLP).
The court held that the continued reporting of dividend income and tax deducted at source (TDS) against the erstwhile company's PAN did not justify reassessment, as the company had ceased to exist and the corresponding income had been disclosed by its successor LLP.
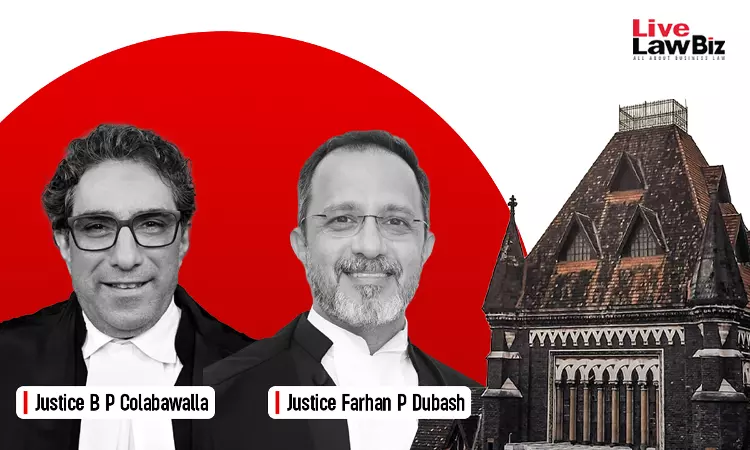
A Division Bench of Justice B.P. Colabawalla and Justice Farhan P. Dubash observed that there was no material to suggest that income had escaped assessment under the erstwhile company's PAN.
“There could not have been any information or reason to suggest that any income in the PAN of the erstwhile company had escaped assessment. Therefore, the show cause notice under Section 148A(1), the order under Section 148A(3) and the impugned notice under Section 148, could not have been issued against the PAN of the erstwhile company, and therefore, have to be quashed and set aside.”, it ruled.
The court also held that reassessment proceedings cannot be initiated merely to verify transactions without material suggesting escapement of income.
“It is settled law that there must be material suggesting escapement of income; an assessment cannot be reopened merely to undertake verification. Under the erstwhile law the Assessing Officer was required to form a 'reason to believe' whereas under the new regime, the sine qua non to issue the notice is 'information suggesting income escaping assessment'. Thus, there has to be a suggestion as to escapement of income. When an Officer wants to make a detailed verification during the reassessment proceedings, then there is no suggestion of escapement of income at all. This is precisely what the courts have held to be impermissible i.e., reassessment proceedings cannot be initiated merely for fishing and roving enquiries or verification purposes.”
The case concerned Aavkar Trade Consultants Private Limited, which was converted into Aavkar Trade Consultants LLP with effect from November 13, 2018. Following the conversion, the company ceased to exist.
Certain deductors nevertheless continued to deduct and deposit tax against the company's old PAN instead of the LLP's PAN. The Department's information showed that dividend income of ₹5.76 lakh had been reported against the old PAN during FY 2021-22.
Since no return had been filed against that PAN for AY 2022-23, the case was flagged as a non-filer under the Department's Risk Management Strategy. The Department subsequently issued a notice under Section 148A(1) of the Income Tax Act, 1961.
The LLP told the Assessing Officer that the company had ceased to exist and that the corresponding dividend income had already been disclosed in its return. It also furnished a transaction-wise reconciliation of the dividend income and TDS reported against the old PAN.
However, the Assessing Officer proceeded with reassessment, observing that the LLP's claims required detailed verification of its books of account, investment records, demat accounts and corporate records.
The High Court noted that the Department had been informed about the conversion and that the LLP had filed its return for AY 2022-23, declaring a total income of ₹2.33 crore, including dividend income. It held that the absence of a return against the erstwhile company's PAN could not justify treating it as a non-filer when the company no longer existed.
The bench also found that the Assessing Officer had failed to properly consider the reconciliation furnished by the LLP. Instead, the officer had sought comprehensive verification during reassessment without identifying any specific transaction or discrepancy suggesting that income had escaped assessment.
The court further observed that the Assessing Officer was required to independently examine the information flagged under the Risk Management Strategy and deal with the LLP's explanation before initiating reassessment. Proceeding without considering the company's conversion and the successor LLP's tax disclosures showed non-application of mind.
The High Court accordingly quashed the notice under Section 148A(1), the accompanying Risk Management Strategy information, the order under Section 148A(3) and the reassessment notice under Section 148.
For Petitioner: Advocate Dharan Gandhi
For IT Dept: Advocate Mamta Omle appeared for the Income Tax Department.