
No Reassessment If Entire Payment Already Disallowed In Earlier Assessment: Delhi High Court
Kapil Dhyani
12 Oct 2026 3:27 PM IST
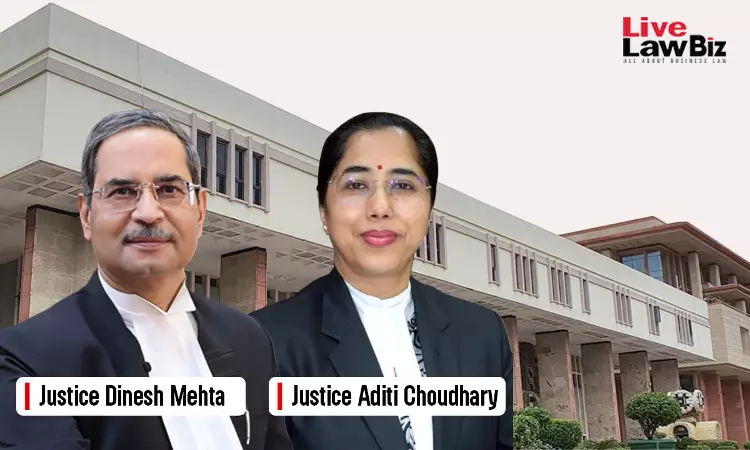
The Delhi High Court has prima facie observed that reassessment proceedings under Section 148 of the Income Tax Act, 1961 may not be permissible where the entire amount in question had already been disallowed in an earlier assessment, as there would prima facie be no income escaping assessment.
The Division Bench of Justices Dinesh Mehta and Aditi Choudhary made the observation while hearing a writ petition challenging a notice issued to Petitioner under Section 148A(1), an order under Section 148A(3) and the consequential notice under Section 148 for Assessment Year 2021-22.
The dispute arose from a payment of Rs.4,31,28,225/- made by Petitioner to M/s KKM Management Centre Middle East (FZE). During an earlier assessment for AY 2020-21 under Section 153C read with Section 143(3), the entire payment had been disallowed on the allegation that it represented bogus purchases.
Subsequently, the Assessing Officer initiated reassessment proceedings under Section 148A, alleging that an amount of Rs.1,91,50,000/- paid to the same entity was liable to be disallowed under Section 40(a)(i) of the Act on account of non-deduction of tax.
Petitioner contended that once the entire payment had already been disallowed, any further disallowance out of the same amount would result in double taxation.
It was submitted that this objection had been raised before the Assessing Officer, but the reassessment proceedings were nevertheless continued on the ground that the proposed disallowance was based on a fresh reason—non-deduction of tax.
Petitioner's counsel submitted that the fundamental issue was whether, in the absence of the jurisdictional fact of income escaping assessment, the Assessing Officer could invoke Section 148 of the Act.
Revenue on the other hand argued that the issue of disallowance under Section 40(a)(i) had not been examined during the earlier assessment proceedings. It contended that although Petitioner had challenged the earlier disallowance before the appellate authority, the Assessing Officer's power to make a disallowance on an additional ground could not be taken away merely because Petitioner might ultimately succeed in its appeal.
After hearing the parties, the High Court was of the prima facie view that “Since the total payment of Rs.4,31,28,225/- had already been disallowed, there remains no income which has escaped assessment.”
It further observed that the jurisdictional fact of income escaping assessment appeared to be absent and, consequently, the Assessing Officer could not assume jurisdiction or invoke Section 148 of the Act.
As such, the Court stayed the impugned proceedings and asked Revenue to file its reply within eight weeks.
The matter is now listed on February 2, 2027.
For Petitioner: Senior Advocate Sachit Jolly, with Advocates Mansha Anand, Sohum Dua, Abhyudaya Shankar Bajpai, Saloni Ray, Shunaim Siddiqui,Yahavi Sharma and Manvi,
For Respondents: Indruj Singh Rai, SSC with Sanjeev Menon, Rahul Singh and Priya Sarkar, JSCs. with Advocates Gaurav Kumar and Prateek Bhati,