
Delhi High Court Quashes 2024 Reassessment Notice For AY 2010-11, Says It Is Beyond 10-Year Limit
Kapil Dhyani
2 Oct 2026 2:29 PM IST
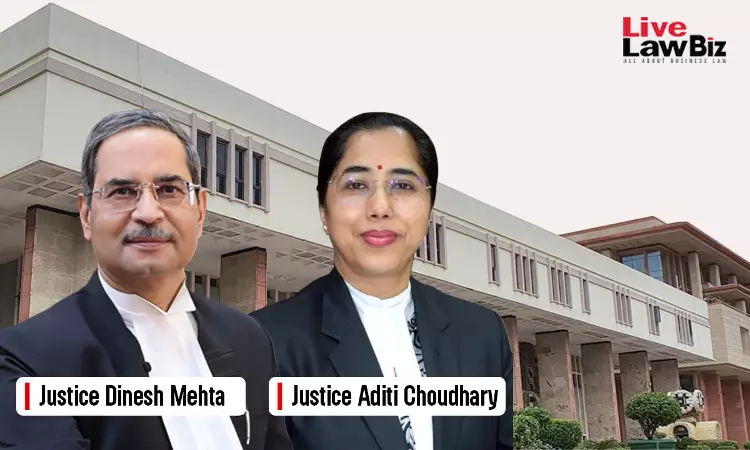
The Delhi High Court on 30 September held that proceedings under Section 153C of the Income-tax Act, 1961 cannot be initiated beyond the limitation period prescribed under Sections 153A and 153C, and quashed a notice issued for Assessment Year (AY) 2010-11.
A Division Bench of Justices Dinesh Mehta and Aditi Choudhary allowed a petition challenging the notice dated 15 February 2024, issued under Section 153C pursuant to a satisfaction note recorded by the Assessing Officer on 7 February 2024. The judges observed that the “impugned notice is, thus, time-barred.”
The petitioner contended that the notice was issued beyond the prescribed limitation period for AY 2010-11 and relied on the High Court's earlier judgment in Principal Commissioner of Income Tax-1 (Central-1) v. Ojjus Medicare Pvt. Ltd. (2024).
The Income Tax Department did not dispute the factual position but submitted that a Special Leave Petition against the Ojjus Medicare judgment was pending before the Supreme Court.
The High Court noted that the satisfaction note in the present case was recorded on 7 February 2024, falling in AY 2024-25, while the impugned notice dated 15 February 2024 concerned AY 2010-11.
Further, the Bench observed that since the escaped income was stated to exceed Rs. 50 lakh, the applicable limitation period was 10 years. Counting backwards from AY 2024-25, the tenth year was AY 2015-16. Proceedings in respect of AY 2010-11 were therefore beyond the permissible period.
Accordingly, the High Court quashed the impugned notice.
For Petitioners: Mr.Ruchesh Sinha, Mr.Dhanajay Bhardwaj, Ms.Diya Sharma, Ms.Upasna Vashistha, Advs.
For Respondents: Mr. Abhishek Maratha, SSC with Mr. Apoorv Agarwal and Mr.Viplav Acharya, JSCs, Mr.Bhanukaran Singhh Mr.Alok Shukla, Advs.