Punjab and Haryana High Court Upholds VAT ITC Restrictions On Cotton Used In Interstate Sales
Mehak Dhiman
3 Nov 2026 2:45 PM IST
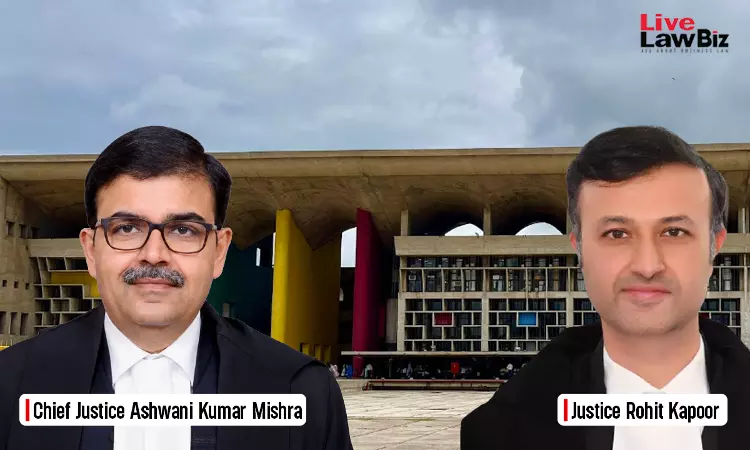
The Punjab and Haryana High Court on 13 October upheld restrictions on claiming Input Tax Credit (ITC) on cotton and products manufactured from goods specified in Schedule H of the Punjab Value Added Tax Act, 2005, when sold in interstate trade, for periods covered by the 2008 amendment to the Act.
A Division Bench comprising Chief Justice Ashwani Kumar Mishra and Justice Rohit Kapoor dismissed appeals involving Fertichem Cotspin Ltd., Grospinz Fab Ltd. and Modern Rice Mills Ghanaur, while remitting other matters to the VAT Tribunal for reconsideration. It said:
“The provision specifically deals with goods specified in Schedule-H which includes 'cotton'. Sub-Section (5) of Section 19 restricts the benefit of ITC on goods specified in Schedule-H or the products manufactured therefrom, to the extent of Central Sales Tax chargeable under the Act of 1956. However, the scope of sub-section (5) has to be examined with reference to the statutory language applicable during the relevant period.”
The appeals arose from disputes involving manufacturers who claimed ITC on purchases of goods, including cotton and paddy, used in manufacturing or processing activities. Subsequently, they sold the manufactured or processed goods in interstate trade. The tax department restricted or denied the credit by relying on Section 19(5) of the Act.
In the lead matter, Fertichem Cotspin Ltd., a manufacturer of 100% cotton yarn, purchased ginned and pressed cotton, a Schedule H commodity, from registered dealers in Punjab and also made purchases from outside the State. It used the cotton to manufacture yarn, which it sold in interstate trade against payment of Central Sales Tax (CST).
For the assessment year 2009-10, Fertichem claimed ITC on VAT paid on local purchases under Section 13 and entry tax paid on interstate purchases under Section 13A. The Assessing Authority applied Section 19(5), reversed ITC of Rs. 36,62,329, allowed credit of Rs. 14,23,774 and raised a demand of Rs. 36,87,828, including penalty.
It also raised an additional demand of Rs. 66,400 under the Central Sales Tax Act. The first appellate authority and the Tribunal upheld the department's view.
The Court observed that the amendment to Section 19(5), which took effect on 28 March 2008, expanded the restriction to cover goods specified in Schedule H and products manufactured from those goods when sold in interstate trade.
Therefore, it stated that the restriction depended on the nature of the goods and the manner in which the manufactured products were sold. Payment of VAT on the purchases or purchase from a subsequent dealer did not, by itself, exclude the restriction.
Further, the Bench distinguished the legal position before the amendment, when Section 19(5) linked the restriction to goods liable to purchase tax under Section 19(1). For those earlier periods, the authorities had to determine whether the purchases were first or subsequent purchases and whether they attracted purchase tax under Section 19(1). It held:
“Post amendment however, Section 19(5) expressly covers 'goods specified in Schedule H, or products manufactured therefrom, when sold in the course of inter-State trade or commerce'; therefore, pleading that payment of VAT or the fact that the purchase was from a subsequent/last dealer does not, by itself, exclude the restriction.”
Applying the amended provision, the Court dismissed the appeals involving Fertichem Cotspin Ltd., Grospinz Fab Ltd. and Modern Rice Mills Ghanaur.
In the appeal filed by T C Terrytex Ltd., the Bench directed the VAT Tribunal to identify the goods for which the company claimed the disputed ITC. As the credit related to yarn, it asked the Tribunal to examine the claim under the applicable statutory provisions.
The judges also disposed of appeals filed by Louis Dreyfus Company India Pvt. Ltd. and Fertichem Cotspin Ltd. concerning periods before the amendment. They directed the Tribunal to determine whether the purchases were first or subsequent purchases and, if subsequent purchases did not attract purchase tax under Section 19(1), consider the ITC claims accordingly.
Accordingly, the High Court upheld the ITC restrictions for periods governed by the amended provision and directed the Tribunal to re-examine claims relating to earlier periods.
For Appellant: Mr. Sandeep Goyal, Senior Advocate, assisted by Mr. Rishab Singla and Ms. Aakriti, Advocates
For Respondent: Mr. Saurabh Kapoor and Mr. R. S. Pandher, Additional Advocates General