
Mobile Chargers Remain Independent Accessories, Toner And Cartridges Are Consumables: Patna High Court
Mehak Dhiman
12 Oct 2026 4:31 PM IST
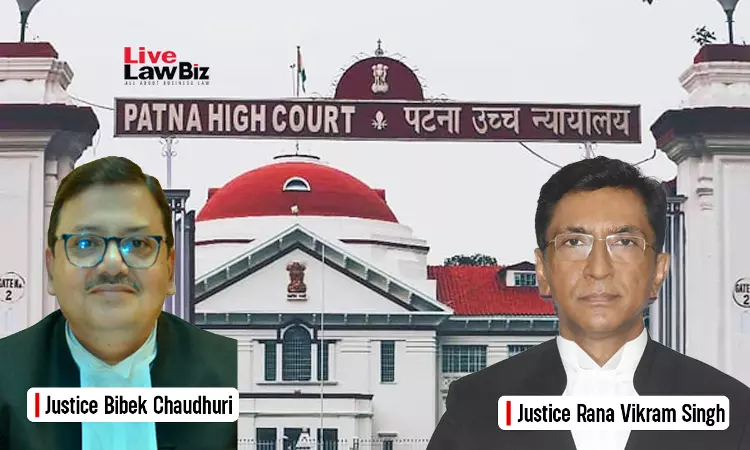
The Patna High Court on 9 October held that mobile chargers sold with cellular phones in composite packs attract VAT at the residual rate of 13.5%, as they qualify as independent accessories rather than parts of the phones.
A Division Bench of Justices Bibek Chaudhuri and Rana Vikram Singh also held that toner and cartridges do not qualify for lower VAT rates applicable to computer peripherals and their parts and accessories, and dismissed appeals filed by Ingram Micro-India Private Limited against a common order of the Commercial Taxes Tribunal, Bihar. It held:
“The Hon'ble Supreme Court was fully conscious that the charger was being sold in a composite pack. It nevertheless held that the charger retained its character as an independent accessory.”
The dispute arose when the tax authorities classified mobile chargers supplied with cellular phones as independent accessories taxable at 13.5%, instead of applying the 5% rate applicable to cellular phones. They assigned a notional value to the chargers and raised a differential tax demand for the financial years 2012-13, 2013-14 and 2014-15.
Ingram Micro argued that it sold phones and chargers in a single package under one maximum retail price (MRP) and one tax invoice, without separately pricing the charger. It contended that the charger formed an integral part of the phone, particularly when the phone was compatible only with the accompanying charger and warranty conditions required its use.
It also argued that the Bihar Value Added Tax Act, 2005, did not permit the authorities to split a single-price composite package and assign a separate value to the charger.
Rejecting these arguments, the Court relied on the Supreme Court's decision in State of Punjab v. Nokia India Pvt. Ltd., which held that a mobile charger is an accessory and not a part of a cellular phone. The Supreme Court had clarified that selling a charger and a phone in a composite package does not convert them into a single taxable commodity.
The Bench observed that a single MRP, exclusive compatibility and warranty conditions did not change the charger's fundamental character as an independent commercial commodity. It also noted that Ingram Micro itself sold standalone chargers at the residual rate of 13.5%, reinforcing their classification as distinct goods. It held that “the mobile charger sold as part of a composite pack remains an accessory taxable at the residual rate.”
It declined to follow decisions of the Allahabad and Karnataka High Courts that distinguished the Nokia India ruling, noting that those cases concerned differently worded statutory schedules. It held that the Supreme Court's ruling and an earlier decision of a coordinate Bench of the Patna High Court governed the classification under the Bihar VAT Act.
The second issue concerned whether toner and cartridges qualified for lower tax rates under Entries 3 and 4 of Part II of Schedule III, which covered computer peripherals and their parts and accessories, or attracted the residual rate of 13.5%.
Ingram Micro argued that printers qualified as computer peripherals and that toner and cartridges, being necessary for their functioning, should receive the same classification. It relied on decisions of the Madras, Gauhati and Allahabad High Courts that had adopted similar classifications under their respective State VAT laws.
The Court rejected this argument, noting that Entry 97 of the Bihar VAT Schedule expressly excluded toner and cartridges from the description of printing ink. It held that this exclusion indicated the legislature's intention to keep toner and cartridges outside the lower-rate entries.
It also observed that toner and cartridges are consumables that users periodically exhaust and replace, rather than permanent or integral components of printers. It distinguished the Madras High Court's decision in Canon India Private Limited v. State of Tamil Nadu, which classified inkjet and toner cartridges as parts and accessories of printers, because the Bihar VAT Schedule contained a specific exclusion that materially differed from the Tamil Nadu legislation.
It held that toner and cartridges attracted the residual rate of 13.5% and upheld the Tribunal's classification on this issue.
Ingram Micro had also challenged findings concerning trade discounts, entry-tax set-off on opening and closing stock, discrepancies in D-IX declarations and interest under Section 39(4) of the Bihar VAT Act. The Tribunal had remanded these issues to the assessing authority for fresh examination, and the High Court declined to interfere with that direction.
On the D-IX declarations, the Bench observed that the authorities could impose tax only upon establishing actual suppression or misuse. Irregular generation of multiple declarations, without proof of misuse, would not by itself justify tax liability.
It directed the assessing authority to reconsider the remanded issues, give Ingram Micro a reasonable opportunity of hearing and recompute the tax, interest and other liabilities for the financial years 2012-13 and 2013-14.
Accordingly, the High Court dismissed both appeals and upheld the classification of mobile chargers, toner and cartridges at the residual VAT rate of 13.5%.
For Appellants: Advocates Gautam Kumar Kejriwal, Atal Bihari Pandey, Alok Kumar Jha, Mukund Kumar, Amrita Dubey and Aditya Agrawal.
For Respondents: Government Advocate Rajeev Kumar Singh, Vaishali and Vikash Kumar appeared for the State.