
SERVICE TAX

Penalties For Service Tax Default, Suppression Cannot Be Imposed Together: CESTAT Chandigarh
The Customs, Excise and Service Tax Appellate Tribunal (CESTAT), Chandigarh, has held that penalties for failure to pay service tax and for suppressing facts with an intent to evade tax cannot be imposed at the same time.The tribunal set aside the penalty for failure to pay service tax, holding that it could not be imposed alongside the penalty for suppression of facts with an intent to evade tax because the two were mutually exclusive.“As regards the penalty under Section 76, we hold that once...

Recovery Of LC Charges By Non-Banking Entity Not Taxable As Banking Services: CESTAT Delhi
The Customs, Excise and Service Tax Appellate Tribunal (CESTAT), New Delhi has held that the issuance of a Letter of Credit (LC) by a person or body corporate not engaged in banking, financial, or similar activities is not covered under the taxable category of "Banking and Other Financial Services." It ruled that the recovery of LC charges by the State Trading Corporation of India Ltd. (STC) from buyers in High Seas Sale (HSS) transactions is therefore not liable to service tax.A bench of...

CESTAT Hyderabad Holds School Examination Services Exempt From Service Tax, Sets Aside ₹1.94 Cr Demand
The Hyderabad Customs, Excise and Service Tax Appellate Tribunal (CESTAT) on 31 July held that services provided to schools for conducting examinations, including Olympiads and talent search examinations, are exempt from Service Tax as they relate to the conduct of examinations by educational institutions. A Bench comprising Judicial Member Justice Angad Prasad and Technical Member A.K. Jyotishi set aside the Service Tax demand of Rs. 1.94 crore, along with interest and penalties,...
CESTAT Kolkata Holds No Service Tax On Pre-2016 Mining Rights, Sets Aside ₹89.13 Lakh Demand
On 4 August, the Kolkata Customs, Excise and Service Tax Appellate Tribunal (CESTAT) held that service tax cannot be levied on royalty paid for mining rights where the right to extract minerals was granted before 1 April 2016, even if the royalty was paid after that date. A Bench comprising Judicial Member Justice R. Muralidhar and Technical Member K. Anpazhakan set aside the service tax demand of Rs. 89.13 lakh, along with interest and penalties, raised against Roy Engineers, a Bihar-based...

Conversion Of Bare Structures Into Retail Showrooms Is Taxable As “Original Works”: CESTAT New Delhi
On 6 August, the New Delhi Customs, Excise and Service Tax Appellate Tribunal (CESTAT), held that converting bare commercial structures into fully functional retail showrooms constitutes “original works” under the service tax law and not merely completion and finishing services, while also ruling that service tax cannot be levied on forfeited customer advances or insurance compensation received for goods destroyed in a fire. A Bench of Judicial Member Ashok Jindal and Technical Member P.V....
Six Month Limitation For Service Tax Refund Starts From SIPCOT Certificate Date: Madras High Court
The Madras High Court on 14 July held that the six-month limitation period for claiming service tax refund under Section 104 of the Finance Act, 2017 must be calculated from the date on which the taxpayer receives the mandatory certificate from the State Industries Promotion Corporation of Tamil Nadu (SIPCOT), and not from the date on which the Finance Act received Presidential assent. A Division Bench comprising Justices Dr. G. Jayachandran and N. Mala allowed the taxpayer's appeal, set aside...
CESTAT Mumbai Sets Aside Service Tax on Packaged Software Sale, Rules It Is Goods, Not Service
The Mumbai bench of the Customs, Excise and Service Tax Appellate Tribunal (CESTAT) has held that packaged (canned) software is "goods". It therefore ruled that its sale cannot be treated as a taxable service merely because the conditions for claiming the available service tax exemption were not met.A coram of Judicial Member Dr. Suvendu Kumar Pati observed that once packaged software is recognised as "goods" under Article 366(12) of the Constitution, its sale falls outside the definition of...

CESTAT Chandigarh Sets Aside ₹2.39 Crore Service Tax Demand Against SBI Card
The Customs, Excise, and Service Tax Appellate Tribunal (CESTAT), Chandigarh, has set aside a ₹2.39 crore service tax demand against SBI Card and Payment Services Ltd., holding that a show cause notice (SCN) that fails to identify the taxable service, the service recipient or the consideration cannot sustain such a demand. The tribunal observed, "We find that the SCN does not specify as to what was the service rendered by the appellants and to whom and what was the consideration thereon."A bench...
COVID Limitation Extension Can't Revive Time-Barred Service Tax Demands: CESTAT Kolkata
The Customs, Excise, and Service Tax Appellate Tribunal (CESTAT), Kolkata, has ruled that the COVID-19-related extension of limitation cannot revive tax demands that had already become time-barred under the statute. A coram of Judicial Member R. Muralidhar and Technical Member K. Anpazhakan observed, "The subsequent exclusion of limitation during the pandemic cannot revive a cause of action or breathe life into a demand which had already become time-barred under the statute. The law relating to...
Financial Crisis Reasonable Cause To Waive Service Tax Penalty: Madras High Court
The Madras High Court on 27 July held that penalties under the Finance Act, 1994 cannot be imposed where a taxpayer proves a genuine financial crisis as a reasonable cause for delayed payment of service tax, ruling that a Tribunal's finding of financial incapacity based on material on record cannot be interfered with in appeal. A Division Bench of Justices G. Jayachandran and N. Mala dismissed two appeals filed by the GST and Central Excise Department against the CESTAT order that waived...
Labour Contractor Liable For Service Tax Despite Production-Based Payments: CESTAT New Delhi
The New Delhi Customs, Excise and Service Tax Appellate Tribunal (CESTAT) on 31 July held that a labour contractor providing workers to a steel company was liable to pay service tax as the agreement was a manpower supply contract and not a job work arrangement for manufacturing. A Bench of Judicial Member Binu Tamta and Technical Member P.V. Subba Rao dismissed the appeal filed by Padam Charan Guman Singh and upheld the demand of service tax, interest and penalty under Section 78 of the Finance...
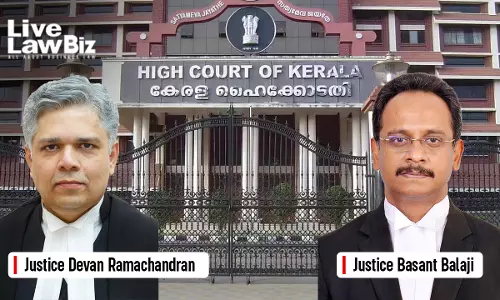
Refund Of Service Tax Cannot Be Decided Before Determining Nature Of Contract: Kerala High Court
The Kerala High Court on 27 July held that the question of refund or adjustment of Service Tax cannot be decided before the Assessing Authority determines whether the underlying contract is a works contract or a service contract, as the nature of the contract determines the applicable tax liability. A Division Bench of Justices Devan Ramachandran and Basant Balaji partly allowed the appeals filed by Gaiagen Technologies Private Limited (formerly Pest Control India Private Limited) and set aside...