
Municipal Commissioner Cannot Alter Property-Tax Categories Without State Sanction: Gujarat High Court
Arvind Kumar Tiwari
3 Oct 2026 1:20 PM IST
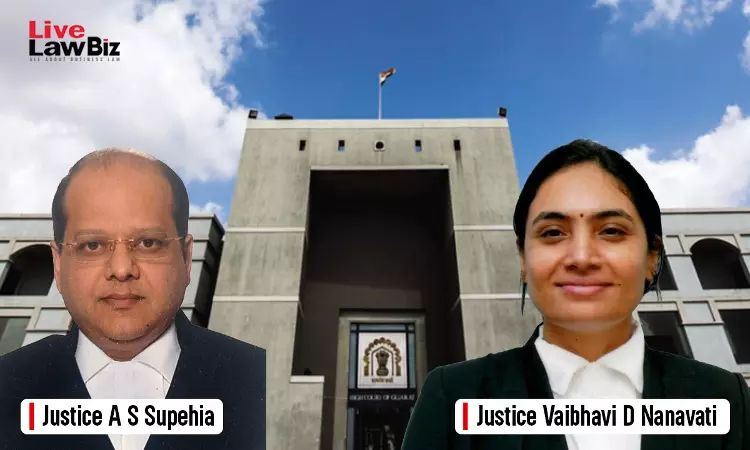
The Gujarat High Court has ruled that a Municipal Commissioner cannot use a carpet-area cut-off to move commercial properties from one property-tax category to another without prior State Government approval.
A Division Bench of Justice A.S. Supehia and Justice Vaibhavi D. Nanavati quashed a March 27, 2015, office order issued by the Bhavnagar Municipal Corporation, which treated shops and showrooms with a carpet area of more than 35 square metres as NU-1 properties. NU-1 properties carry a multiplier of 5, while NU-2 properties carry a multiplier of 3.
The court held that the Commissioner could determine additional buildings within the categories set out in the State-approved Rules but could not use that power to split an existing category on the basis of carpet area and thereby increase the tax burden without State Government sanction.
“However, the same does not, in any manner, permit the rate to be determined by fixing a particular carpet area by which the original Rules determined by the State Government, categorizing the properties into NU-1 and NU-2 categories, gets altered sans its approval,” the court observed.
The dispute concerned property-tax Rules framed by the State Government through a Resolution dated April 2, 2013. The State Government framed the Rules under Section 454 read with Sections 141B and 141AA of the Gujarat Provincial Municipal Corporations Act, approved them under Section 455 and published them in the Official Gazette.
In simple terms, Section 454 empowers the Corporation to make rules for levying property tax, while Section 455 makes State Government sanction necessary for making, adding to, altering or rescinding those rules. Section 455 also requires the rules to be finally published in the Official Gazette.
The 2013 Rules placed different kinds of commercial properties in NU-1 and NU-2 categories. NU-1 carried a multiplier of 5, while NU-2 carried a multiplier of 3.
The Rules also allowed the Commissioner to determine other buildings that could fall within those categories. The court, however, held that this did not mean the Commissioner could create a new split within the categories based on the size of a shop or showroom.
The March 27, 2015 order provided that showrooms and shops with a carpet area of more than 35 square metres would be treated as NU-1. It also stated that all units located in an air-conditioned mall would be treated as NU-1.
The petitioners challenged the move, arguing that the Corporation had effectively changed the State-approved classification without following the procedure under Sections 454 and 455.
The Corporation relied on Section 141B of the Act. That provision allows property tax to be levied on the basis of carpet area and permits the Corporation to increase or decrease the rate after considering specified factors, including the purpose for which non-residential buildings are used.
The court found that this power did not authorise the Commissioner to change the classification itself.
It noted that Section 141B expressly provides a 40-square-meter cut-off for a particular category of residential buildings. There was no corresponding provision prescribing a carpet-area cut-off for non-residential buildings such as the commercial properties covered by NU-1 and NU-2.
The court therefore held that the 35-square-metre criterion altered the classification prescribed by the State Government.
“By introducing the criterion of 35 square metres and above, the Commissioner has, in fact, altered the nature of the properties from the NU-2 category to NU-1, which is impermissible, without the sanction of the State Government under Section 455 of the Act,” the court observed.
The court also noted that the change resulted in enhanced property tax being levied without issuance of public or individual notice. It held that this provided an additional ground to interfere with the Corporation's action.
A subsequent State Government Resolution dated March 31, 2020 introduced fresh Rules, which were published in the Official Gazette. The court noted that after March 31, 2020, property tax was collected without the earlier bifurcation of shops based on the square-metre cut-off introduced by the 2015 order.
The petitions also challenged the retrospective levy of property tax. The petitioners agreed that fresh bills could be issued from specified dates and undertook to pay the outstanding tax from those dates.
The court permitted the Corporation to issue fresh tax bills within 12 weeks of receiving the judgment and directed the authority to consider the High Court's August 16, 2016 decision in Special Civil Application No. 18287 of 2015 before issuing a fresh notice.
If an adverse retrospective-tax order is passed, the petitioners can challenge it before the appropriate forum. The order cannot be implemented for two weeks, and any amount paid by the petitioners is to be adjusted against their outstanding tax liability.
The court quashed the March 27, 2015 office order and all subsequent action taken pursuant to it. It directed the authorities to remove the seals from the properties and allow the petitioners to use them after payment of the outstanding taxes from the dates specified in the judgment.
The court also clarified that these directions are confined to the petitioners in the four cases. Taxpayers who had already paid the taxes without protest cannot have their cases reopened or reassessed.
The writ petitions were accordingly allowed
For Petitioners: Chintan K. Gandhi for Raval & Trivedi Associates; Sandip H. Munjysara
For Respondents: Tanushree Shrimal, AGP; H.S. Munshaw; Dr. Venugopal H. Patel