
Central Sales Tax | Form H Must Be Filed By Time Of Assessment To Claim Tax Benefit: Andhra Pradesh High Court
Mehak Dhiman
16 Oct 2026 11:39 AM IST
The Andhra Pradesh High Court has recently held that dealers must submit Form H declarations by the time of assessment by the first assessing authority to claim a tax benefit on the last sale of goods preceding an export.
The Full Bench clarified that the extended filing period available for Forms C and F under the Central Sales Tax (Registration and Turnover) Rules, 1957, does not apply to Form H declarations.
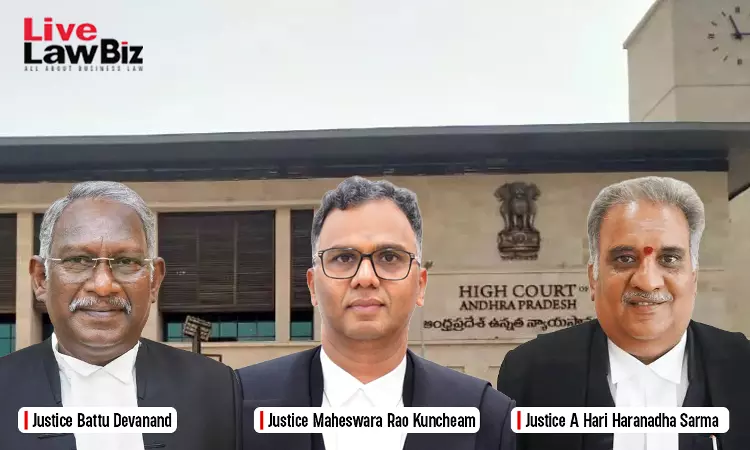
A three-judge Bench of Justice Battu Devanand, Justice Maheswara Rao Kuncheam and Justice A. Hari Haranadha Sarma delivered the ruling while answering a reference arising from a batch of writ petitions concerning the time limit for submitting Form H declarations.
Form H is a declaration used to claim a tax benefit on the last sale of goods before they are exported to another country. Under the Central Sales Tax Act, this sale may be treated as a sale in the course of export, subject to certain conditions.
The dispute arose under Rule 12 of the Central Sales Tax (Registration and Turnover) Rules, 1957. Rule 12(7) allows Forms C and F to be submitted within three months after the end of the relevant period. It also permits the prescribed authority to allow additional time if sufficient cause prevented a dealer from submitting the forms within that period.
The question before the Court was whether this extension could also apply to Form H declarations.
The petitioners argued that Rule 12(10)(b), which applies certain State rules governing Form C to Form H, supported extending the same facility to Form H declarations. They also contended that dealers should not be penalised for the absence of a separate State procedure governing the submission of Form H.
The State opposed this argument, submitting that Rule 12(10)(a) specifically requires Form H to be furnished to the prescribed authority by the time of assessment by the first assessing authority.
Accepting the State's interpretation, the Court held that Rule 12(10)(a) specifically governs the deadline for Form H, while Rule 12(10)(b) deals with other matters, including the authority and conditions for obtaining the form, its custody, record-keeping and use.
The Bench observed,
“Therefore it is clear that with regard to time, Rule 12[10(a)] alone is applicable and Rule 12(7) is not applicable. Even if it is to be accepted that CST ( R&T) Rules, 1957 are made for Andhra Pradesh invoking Section 13 (3) (4) (5) of CST Act, 1956 no rule is found indicating the time prescribed covering or applicability to Form H. Therefore, the claim that time contemplated under Rule 12(7) would extend to Rule 12(10) and to Form H also found not acceptable.”
It therefore concluded,
“In view of the discussion made above, the reference is answered holding that time prescribed under Rule 12(7) of CST (R&T) Rules, 1957 as to submission of declaration forms in Form 'C' and Form 'F' within three months after the end of the period to which the declaration relates to, does not extend to Form H and the benefit under the Rule 12[10 (b)] does not apply to invoke the parity between the Form C and Form H particularly with regard to time limit, when Rule 12[10 (a)] is very clear that the declaration referred under Section 5(4) shall be in Form H and shall be furnished to the prescribed authority up to the time of assessment by the first assessing authority.”
The Court disposed of the writ petitions in those terms.
For the petitioners, M.V.J.K. Kumar, P. Balaji Varma, Srinivasa Rao Kudupudi, K. Raji Reddy, A. Sarveswar Rao, K. Adi Siva Vara Prasad, G. Narendra Chetty, Peddibhotla Venkata Sai Rajesh and Dr. D. Venkata Ramana Reddy, among others.
For the State, the respective Government Pleaders for Commercial Tax, along with Special Standing Counsel Shaik Jeelani Basha and S. Suribabu, among others.