
Timely Reassessment Notice Cannot Cure Invalid Income Tax Sanction: Gujarat High Court
Arvind Kumar Tiwari
24 Oct 2026 1:03 PM IST
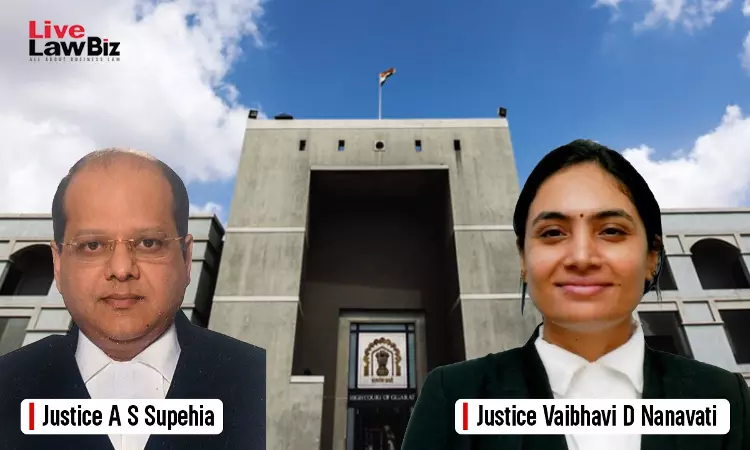
The Gujarat High Court has quashed a tax reassessment, ruling that a timely notice to a taxpayer cannot cure an approval obtained from the wrong authority.
The court held that the tax department could not rely on the time given to the taxpayer to respond to a reassessment notice to justify the sanction granted by the Principal Commissioner of Income Tax.
The tax department argued that excluding this period meant the approval granted by the Principal Commissioner of Income-tax was valid. The court rejected this interpretation, holding that a 2023 amendment to the Income-tax Act could not retrospectively validate the sanction.
“The Revenue cannot validate its action by arguing that a timely Section 148A(b) notice cures an untimely Section 151(i) sanction. This contention contradicts the statutory framework of Section 149(1)(a) read with Section 151 (prior to 01.04.2023). Because Section 151 clearly demarcates which authority must grant sanction based on the timeline, the strict limitation periods under Section 149(1)(a) and (b) cannot be blurred or compromised. If the justification of the revenue is accepted then there was no need for the legislature to introduce the proviso under Section 151, w.e.f. 01.04.2023 bringing the adjustment of period within the ambit of Section 151(1) since such adjustment already existed under Section 149. The legislature was conscious of clear delineation of the specified authority under Section 151 having direct nexus with Clauses (a) and (b) of Section 149(1), and the provisos appended therein,” the court observed.
A bench of Justice A.S. Supehia and Justice Vaibhavi D. Nanavati quashed the reassessment order and notice issued to Ritaben Arvindbhai Patel for assessment year 2018-19. The court held that the Principal Commissioner of Income-tax (Central), Surat, could not grant the sanction on April 1, 2022, because the ordinary three-year period had expired on March 31, 2022.
The case concerned a proposed reassessment of ₹29.42 lakh in alleged escaped income. The proceedings followed a survey at Saral Infra's premises on April 18 and 19, 2019, during which documents, diaries, and notebooks were impounded. The tax department also relied on a statement recorded from Sunilbhai M. Patel under Section 131, concerning land transactions.
Patel challenged the reassessment, arguing that more than three years had elapsed from the end of assessment year 2018-19 by the time the sanction was granted. She contended that approval was therefore required from the higher authority specified under Section 151(ii), rather than the Principal Commissioner under Section 151(i).
The tax department argued that the nine days allowed to Patel to respond to a notice should be excluded when calculating the limitation period. It maintained that this extended the deadline to April 9, 2022, and left the Principal Commissioner competent to grant approval. It also argued that the 2023 amendment was clarificatory and should apply retrospectively.
The court rejected the department's interpretation. It held that the exclusions relied on by the Revenue under Section 149 did not apply to the limitation period under Section 149(1)(a) in this case. The court noted that the relevant exclusions under the provisions then in force concerned cases covered by Section 149(1)(b), which applied to alleged escaped income exceeding ₹50 lakh.
The Finance Act, 2023, introduced a proviso to Section 151 to account for periods excluded or extended under specified provisions of Section 149 when determining the authority competent to grant approval. However, the amendment took effect only on April 1, 2023.
Relying on the Supreme Court's decision in CIT v. Vatika Township Private Limited, the court held that the amendment operated prospectively, particularly because the legislature had expressly specified its effective date. It could not validate the sanction granted in Patel's case in 2022.
The court also referred to the Supreme Court's ruling in Union of India v. Rajeev Bansal, which recognised that obtaining approval from the competent authority under Section 151 is a jurisdictional requirement for issuing a reassessment notice.
Separately, the court found that the material relied on by the tax department did not establish Patel's connection with the alleged on-money transactions. The documents impounded during the survey did not name her or contain particulars establishing her involvement.
The court noted that Patel had sold the land to two other purchasers, not Sunilbhai Patel. The tax department had also produced no material to establish that Sunilbhai Patel acted as her broker.
Finding no live link between Patel and either Saral Infra or Sunilbhai Patel, the court held that the reassessment also failed on merits.
It allowed the writ petition and quashed the order under Section 148A(d) and the consequential notice under Section 148. Both were dated April 1, 2022.
For Petitioner: Tushar Hemani, Senior Advocate, with Vaibhavi K. Parikh
For Respondent: Rutvij Patel and Karan G. Sanghani, Senior Standing Counsel