ITAT's Findings On Comparable Companies Cannot Be Disturbed Without Perversity: Karnataka High Court
Mehak Dhiman
4 Nov 2026 3:25 PM IST
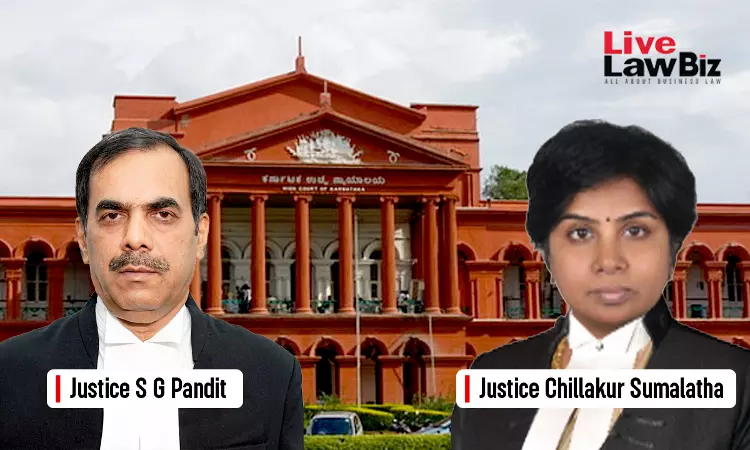
The Karnataka High Court on 15 October held that findings of the Income Tax Appellate Tribunal (ITAT) on the selection or exclusion of comparable companies in transfer pricing proceedings cannot be interfered with unless the Revenue establishes perversity.
A Bench of Justices S.G. Pandit and Chillakur Sumalatha dismissed the Income Tax Department's appeal against Trident Microsystems India Pvt. Ltd., upholding the ITAT's decision to exclude functionally dissimilar companies from the list of comparables for determining the Arm's Length Price (ALP). The judges held:
“...the appellants-Revenue has failed to demonstrate the perversity and how the Assessee-Genesys International Corporation Limited performs similar function as that of the respondent-Assessee. Therefore, the said question is answered against the appellants-Revenue and in favour of the respondent-Assessee…”
The Revenue had challenged the ITAT's order dated 14 August 2020, for Assessment Year 2012-13, in an appeal under Section 260A of the Income Tax Act, 1961.
It questioned the exclusion of Genesys International Corporation Ltd. as a comparable on the ground of functional dissimilarity. It also challenged the application of a turnover filter and the exclusion of other comparable companies despite the Transfer Pricing Officer (TPO) having considered them suitable.
The Court relied on its decision in SAP Labs India Private Limited v. Income Tax Officer, in which a Coordinate Bench had examined the principles governing transfer pricing and the selection of comparable companies.
It observed that Chapter X of the Income Tax Act constitutes a self-contained code governing transfer pricing. It held that the selection or exclusion of comparables must comply with Rule 10B of the Income Tax Rules, 1962. The TPO cannot reject the taxpayer's comparables merely to replace them with a standard set of companies selected by the Department.
On the turnover filter, the Bench noted that the Coordinate Bench in SAP Labs had held that, in the absence of a statutory prescription fixing an upper or lower turnover limit, the Tribunal's adoption of an upper turnover filter of Rs. 200 crore was not arbitrary, as it rested on a rational and logical basis.
It also found that the Revenue had failed to establish how Genesys International Corporation Ltd. performed functions similar to those of the respondent or demonstrate any perversity in the Tribunal's findings.
With respect to the other comparable companies, the judges noted that the Tribunal had examined their functional profiles, assets and risks against those of the respondent before directing their exclusion. They held:
“..The Tribunal on taking note of the functionality of the comparable companies and the respondent-Assessee company and also taking note of the functions, assets and risks assumed by the comparable companies as well as the respondent-Assessee company, has rightly come to the conclusion that comparables are functionally dissimilar and rightly directed exclusion of those comparables..”
Further, the Bench observed that the Revenue had failed to establish that the Tribunal had relied on irrelevant material or ignored relevant material while arriving at its conclusions.
Accordingly, the High Court answered all three substantial questions of law against the Revenue and in favour of the respondent, and dismissed the appeal.
For the Revenue: Mr. E.I. Sanmathi, Advocate.
For the Assessee: Unrepresented.