
Karnataka High Court Rejects Insurer's Plea For TDS On Motor Accident Interest, Says It Isn't Taxable
Mehak Dhiman
19 Nov 2026 3:14 PM IST
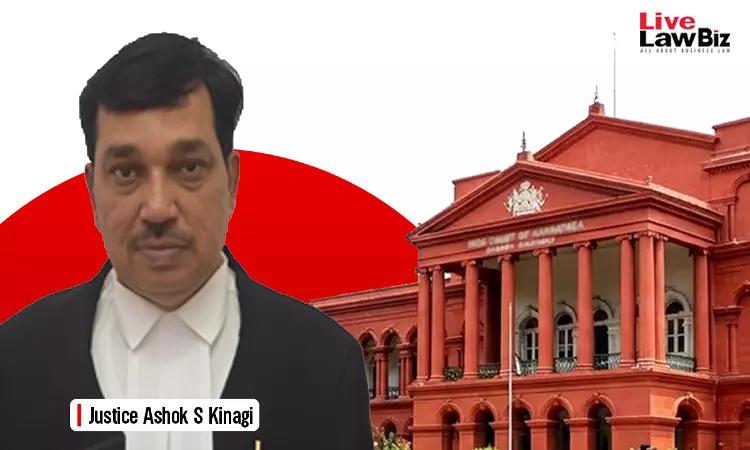
The Karnataka High Court on 11 November dismissed a writ petition filed by Oriental Insurance Company Limited challenging an order passed by the Principal District and Sessions Judge, Bidar, on 20 July 2023, which declined to direct TDS deduction on the interest component of motor accident compensation.
Justice Ashok S. Kinagi held that interest awarded on motor accident compensation from the date of filing the claim petition until the award does not constitute taxable income and is not subject to tax deduction at source (TDS). The Bench said:
“Though an amendment was made to Section 194 of the Income Tax Act, including the enhancement of monetary threshold by Finance Act, 2026, that does not alter the fundamental position. The charging provision remains unaltered and therefore, the amendment has no bearing on the present controversy.”
The insurance company contended that it was liable to deduct TDS under Section 194A(1) of the Income Tax Act, 1961, and that the Executing Court had erred in refusing to direct such deduction. It sought to set aside the order on this ground.
The Court observed that Section 194A permits TDS deduction only where the payment itself constitutes taxable income. Interest awarded from the date of filing the claim petition until the award remains an incident of compensation and does not acquire the character of taxable income.
It noted that the issue stood covered by its earlier decisions in United India Insurance Co. Ltd. v. Seema Begum, Oriental Insurance Co. Ltd. v. Smt. Laxmavva alias Laxmi and Balaji Corporate Services v. Union of India.
The Bench also relied on the Bombay High Court's decision in Rupesh Rashmikant Shah v. Union of India, which held that Section 194A does not determine the taxability of a receipt and that interest awarded by a Claims Tribunal for delayed determination of compensation does not attract TDS.
It observed that although the Finance Act, 2026 amended Section 194A, including by enhancing the monetary threshold, the amendment did not alter the fundamental legal position since the charging provision remained unchanged.
Accordingly, the High Court dismissed the writ petition, finding no grounds to interfere with the Executing Court's order.
For the Petitioner: Advocate Preeti Patil Melkundi.