
'Assessee In Default Has Not Committed A Sin': Delhi High Court Orders ₹1.93 Crore Tax Refund
Kapil Dhyani
28 Oct 2026 7:51 PM IST
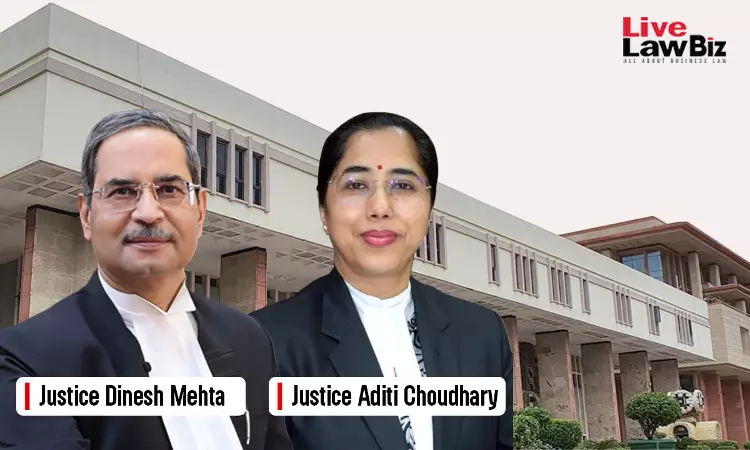
The Delhi High Court has directed the Income Tax Department to refund ₹1.93 crore, with applicable interest, to a taxpayer after holding that the recovery of the amount during the pendency of stay applications was a “colourable exercise of power.”
The division bench of Justices Dinesh Mehta and Aditi Choudhary observed that merely because an assessee had been declared to be in default did not mean that they had committed a sin so as to be deprived of the benefit of circulars issued by the Central Board of Direct Taxes (CBDT).
"Simply because the petitioner had been declared to be an assessee in default, does not mean that he has committed a sin so as to be deprived of the benefit of CBDT circular", the court observed.
“The circulars issued by CBDT are binding upon the Assessing Officer,” the court added.
The Court was hearing a writ petition filed by one Mohan Clothing, which challenged the recovery of income tax dues for the assessment year 2020-21 while its appeal against the assessment order remained pending before CIT(A).
The Assessing Officer had raised a demand of approximately ₹7.54 crore against the company. After the company filed an appeal in October 2022, the Department adjusted a refund of ₹6.20 crore due to it for the assessment year 2022-23 against the outstanding demand.
The company contended that the adjustment was made without providing it an opportunity to respond and exceeded the 20% recovery limit prescribed under CBDT memoranda dated February 29, 2016, and July 31, 2017.
The Department argued that the company had not initially filed a stay application before the competent authorities and that the CBDT memoranda, therefore, did not apply. It also submitted that the company had been declared an assessee-in-default and that the recovery could not be undone merely because an appeal was pending.
The Court declined to order a refund of the initial recovery of ₹6.20 crore, noting that the company had not sought a stay before the competent authorities at the relevant time and that more than three years had passed since the amount was recovered.
However, it took a different view of the subsequent recovery of ₹1,93,15,522, made on February 18, 2025.
The Court noted that the company's stay application was pending before the appellate authority as well as the High Court when the subsequent recovery was made. The company had also responded to a notice issued by the Assessing Officer, pointing out that more than 80% of the demand had already been recovered and requesting that further recovery be kept in abeyance.
The Court observed that the Assessing Officer had ignored the company's representation despite the applicable CBDT circulars and the legal position.
It also noted that an intimation under Section 245 of the Income Tax Act, 1961, was necessary before adjusting the refund, but no such intimation was found on record.
As such, the Court partly allowed the petition and directed the AO to refund ₹1,93,15,522, along with applicable interest, within 30 days.
The Court further directed the Principal Chief Commissioner of Income Tax, Delhi, to send a copy of the judgment to the officer who had effected the recovery. It said the officer's reporting authority could consider placing a copy of the order in the officer's service book.
For Petitioner: Advocates Ananya Kapoor, Sumit Lalchandani,Tanmay Doneria
For Respondents: Gaurav Gupta, SSC, Shivendra Singh, Yojit Pareek, JSCs; Advocate Surya Jindal