Assessing Officer's Location Determines Appeal Jurisdiction, Not ITAT Bench: Karnataka High Court
Mehak Dhiman
3 Nov 2026 3:46 PM IST
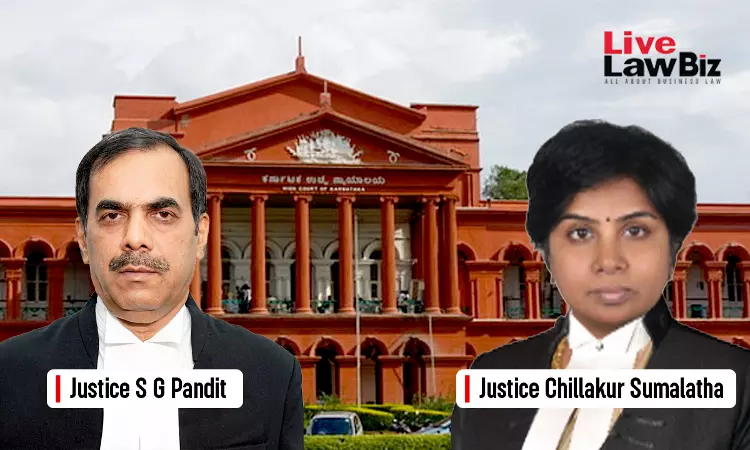
The Karnataka High Court has held that the jurisdiction to hear an appeal against an Income Tax Appellate Tribunal (ITAT) order under Section 260A of the Income Tax Act, 1961, depends on the territorial jurisdiction of the Assessing Officer who passed the assessment order, and not the location of the Tribunal.
A Division Bench of Justices S.G. Pandit and Chillakur Sumalatha dismissed the Income Tax Department's appeal against an ITAT order in the matter of Shaw Wallace Financial Services Ltd., subsequently taken over by United Spirits Ltd., as not maintainable before the Karnataka High Court. It said:
“..the jurisdiction to challenge the decision of the ITAT shall be decided based on the assessment order. To file an appeal before the High Court under Section 260A of the Act, assessment order would become relevant and not the decision of the ITAT...”
The Department had challenged the ITAT's order dated 28 August 2019, concerning Assessment Year 2004-05. The appeal raised two substantial questions of law: whether gains from the sale of shares of RITPL constituted long-term capital gains rather than business income, and whether professional fees of Rs. 6,94,29,123 paid to M/s Kinsley & Co. were deductible.
Senior Advocate Mistri Jehangir, appearing for United Spirits, questioned the maintainability of the appeal before the Karnataka High Court. He submitted that the Assessing Officer had passed the assessment order in Kolkata and, therefore, the appeal could only lie before the High Court having territorial jurisdiction over that officer.
The Revenue opposed the objection, arguing that the ITAT's Bengaluru Bench had passed the impugned order and that United Spirits had its registered office in Bengaluru. It contended that these factors conferred jurisdiction on the Karnataka High Court.
Rejecting the Revenue's contention, the Court relied on the Supreme Court's decision in Principal Commissioner of Income Tax v. ABC Papers Ltd., which held that an appeal against an ITAT order lies before the High Court within whose territorial jurisdiction the Assessing Officer who passed the assessment order is situated.
The Supreme Court had clarified that the location of the ITAT does not determine the jurisdiction of the High Court, as a Tribunal Bench may exercise jurisdiction over multiple States.
The High Court Bench noted that the Assistant Commissioner of Income Tax, Circle-5, Kolkata, had passed the assessment order for Assessment Year 2004-05 on 27 December 2006. It also noted that the Revenue had enclosed an incorrect assessment order with its appeal. The enclosed order concerned Shaw Wallace Breweries Ltd., rather than Shaw Wallace Financial Services Ltd.
Further, the judges held that United Spirits' subsequent takeover of Shaw Wallace Financial Services Ltd. and its registered office in Bengaluru could not confer territorial jurisdiction on the Karnataka High Court.
Accordingly, the High Court dismissed the appeal as not maintainable, granting the Revenue liberty to approach the jurisdictional High Court in accordance with law.
For the Revenue: Mr. E.I. Sanmathi, Advocate.
For United Spirits: Mr. Mistri Jehangir, Senior Advocate, instructed by Ms. Tanmayee Rajkumar, Advocate.