
Gujarat High Court Holds Company Entitled To Interest On ₹2.50 Crore TDS Refund
Arvind Kumar Tiwari
23 Sept 2026 7:35 PM IST
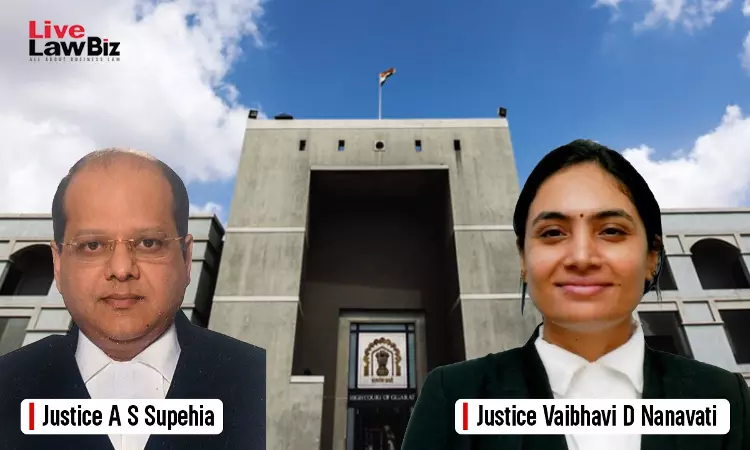
The Gujarat High Court has ruled that Maharashtra Border Check Post Network Ltd. is entitled to interest on a ₹2.50 crore refund arising from a TDS demand that was later set aside.
The court held that the company's claim was covered by Section 244A(1)(b) of the Income Tax Act and could not be denied by relying on Section 244A(1B), which came into effect from April 1, 2017.
A Division Bench of Justice A.S. Supehia and Justice Vaibhavi D. Nanavati observed that Section 244A(1)(b) already provided for interest on refunds in cases falling outside the specific categories covered by Section 244A(1)(a).
The bench held, “The grant of interest on refund already finds place in the statute under the provisions of clause (b) of Section 244A(1) of the Act.”
The case arose from a ₹12.60 crore demand raised against the company after the Assessing Officer treated it as an assessee-in-default for allegedly failing to deduct TDS. The demand comprised ₹6.70 crore towards tax and ₹5.89 crore as interest under Section 201(1A).
The company challenged the action before the High Court. On February 23, 2016, the court quashed the notices and the April 23, 2015 order that had treated the company as an assessee-in-default. The Revenue challenged that decision before the Supreme Court, but its special leave petition was dismissed on September 23, 2016.
The company had, meanwhile, deposited ₹2.50 crore under protest in instalments between September 30, 2015 and February 3, 2017. Its appeal before the Commissioner of Income Tax (Appeals) was also allowed on June 23, 2016, with the appellate authority directing implementation of the High Court's order.
Despite these orders, the court observed that “nothing was done for almost eight months”. The company eventually received an online refund of ₹2.50 crore on February 3, 2017, but no interest was paid.
The company then filed a grievance petition and an application under Section 154 seeking interest on the refund. The claim was rejected on September 26, 2017. It was rejected in view of Section 244A(1B), which had been introduced with effect from April 1, 2017.
Section 244A provides for interest when a refund becomes due to an assessee under the Income Tax Act. Under Section 244A(1)(a), interest applies to specified categories such as advance tax and tax deducted or collected at source. Section 244A(1)(b) covers “any other case” and provides for interest from the date the tax or penalty was paid until the refund is granted.
The court held that the company's refund fell within this latter category. Since Section 244A(1)(b) already covered the situation, the later insertion of Section 244A(1B) could not be used to deny interest.
Section 244A(1B), introduced in 2017, specifically deals with refunds becoming due to a deductor in respect of amounts paid to the Central Government under the TDS provisions. The provision lays down the period from which interest is to be calculated in such cases. The court held that it could not be applied to take away the interest otherwise available to the company under the existing Section 244A(1)(b).
The bench also relied on the Supreme Court's ruling in Union of India v. Tata Chemicals Ltd. In that case, the Supreme Court had observed that when the State receives and retains money without a legal right to do so, the obligation to refund the money carries with it the right to interest.
Applying that principle, the Gujarat High Court observed that the company was entitled to interest on the ₹2.50 crore refund.
The bench also noted that the company had already succeeded before the High Court and the CIT(A), yet had to file another application seeking interest. The claim was then rejected on the basis of a provision introduced later, without properly considering the existing Section 244A(1)(b).
The court allowed the writ petition and directed the Revenue to pay interest on the ₹2.50 crore refund under Section 244A(1)(b) within four weeks. If the direction is not complied with within that period, the amount will carry further interest at 9% per annum.
The Revenue was also directed to pay ₹10,000 as costs. The court later directed that the costs be deposited with the High Court Legal Services Authority within two weeks.
For Petitioner: Advocate Dhinal A. Shah
For Respondent No. 2: Nikunt K. Raval
For Respondent No. 1: Maithili D. Mehta, Senior Standing Counsel