
INCOME TAX
ITAT New Delhi Sets Aside Rejection Of Trust Registration Over Missing Irrevocability Clause
The New Delhi Bench of the Income Tax Appellate Tribunal (ITAT) on 30 April held that absence of an irrevocability clause in a Trust Deed is not, by itself, fatal to registration where the defect is subsequently cured and set aside the rejection of registration of a charitable Trust. A Bench of Judicial Member Raj Kumar Chauhan and Accountant Member Brajesh Kumar Singh allowed the appeal filed by Social Welfare Public Trust and set aside the orders dated 3 December 2025 passed by the...
Receipts From Capital Asset Transfer Cannot Be Taxed Under Residuary Head: ITAT Mumbai
The Mumbai Bench of the Income Tax Appellate Tribunal (ITAT) on 30 April 2026 held that once a receipt is characterised as arising from the transfer of a capital asset, the tax authority cannot reclassify it under the residuary head of income merely because computation under the capital gains provisions is disputed or fails. The Bench comprising Judicial Member Pawan Singh and Accountant Member Makarand Vasant Mahadeokar dismissed the Revenue's appeal against the order of the Commissioner of...
Cash Deposits In Education Trust Account Not Taxable In Individual's Hands: ITAT New Delhi
The Delhi Bench of the Income Tax Appellate Tribunal (ITAT), on 30 April, held that cash deposits in a bank account of a separate legal entity cannot be taxed in an individual's hands merely because he is an authorised signatory, unless there is evidence establishing beneficial ownership or undisclosed income. A Bench comprising Judicial Member Raj Kumar Chauhan and Accountant Member Brajesh Kumar Singh dismissed the Revenue's appeal and upheld the CIT(A)'s order deleting an addition of Rs....
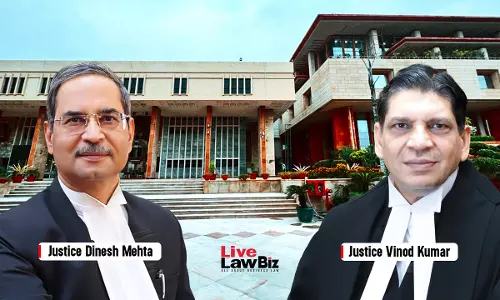
Delhi High Court Refuses To Condone Delay In Late Filing To Opt Lower Corporate Tax Regime
The Delhi High Court has recently refused to condone delay by a company in opting for a concessional corporate tax regime, holding that its application filed beyond the three-year limit prescribed under a CBDT circular was not maintainable.The division bench of Justices Dinesh Mehta and Vinod Kumar thus dismissed the writ petition filed by a company challenging the rejection of its application under Section 119(2)(b) of the Income Tax Act seeking condonation of delay in filing Form 10-IC for...
Gujarat HC Upholds Constitutionality Of CGST Provision Denying ITC To Buyers If Supplier Fails To Pay Tax
The Gujarat High Court has on Friday upheld the constitutional validity of a GST provision that denies input tax credit to a purchaser if the supplier has not deposited the tax with the government. The court upheld the validity of Section 16(2)(c) of the Central Goods and Services Tax Act, 2017, holding that entitlement to input tax credit is conditional upon actual payment of tax to the government. Emphasising that there was no constitutional infirmity in the provision, the court held, ...
Capgemini Not Liable To Pay Advance Tax Interest For Period Before Commencement Of Business: ITAT Mumbai
The Mumbai bench of the Income Tax Appellate Tribunal (ITAT) has held that Capgemini IT Solutions India Private Limited cannot be charged interest for delay in paying advance tax for the period before it started its business in October 2019. “The levy of interest under section 234C in respect of the instalments falling due prior to 17.10.2019 is not sustainable in law.”, it observed.The bench of Judicial Member Kavitha Rajagopal and Accountant Member Makarand Vasant Mahadeokar passed the order...
In Faceless Assessment, Income Tax Revision Cannot Be Decided Without Inquiry: Gauhati High Court
The Gauhati High Court has held that the revisional authority cannot dispose of revision proceedings in a mechanical manner under the Income Tax Act (Section 264), which allows a taxpayer to seek revision of an order through a faceless process without making, or causing, an enquiry. This is especially so where the assessee claims difficulty in producing voluminous records and seeks verification at the place of business. The court referred to an earlier Division Bench ruling that held that...
Appellate Authorities Can Entertain New Claims As Estoppel Does Not Apply In Tax Proceedings: ITAT Chennai
The Chennai bench of the Income Tax Appellate Tribunal (ITAT) has recently reiterated that the principle of estoppel has no application in tax proceedings and appellate authorities can entertain new claims from taxpayers even if they were not made in the original return. “the law is well settled to the extent that the decision of Hon'ble Supreme Court in the Goetze India Ltd. Vs. CIT (2006) 284 ITR 323 (SC) is confined to the power of Assessing Officer alone. There are no fetters on the...
ITAT Chennai Expunges Direction To Reopen Assessments For Years Not Under Appeal
The Chennai Bench of the Income Tax Appellate Tribunal (ITAT) has expunged a direction issued by the Commissioner of Income Tax (Appeals) to reopen the earlier assessments of individual taxpayer Chandanmal Nagaraj, holding that such directions are beyond its powers. The coram comprising Judicial Member Manu Kumar Giri and Accountant Member Inturi Rama Rao passed the order on April 30, 2026. The case related to Assessment Year 2017–18. While granting relief for this year, the CIT(A) had also...

Is India–UK DTAA Benefit Available On Dividend Distribution Tax? Bombay High Court Refers Issue To Larger Bench
The Bombay High Court has referred to a larger bench the question of whether companies paying Dividend Distribution Tax (DDT) can claim the benefit of lower tax rates under the India–UK tax treaty. The court was hearing appeals filed by Foseco India Ltd. challenging the denial of a refund of excess income tax paid. The issue, though arising in the context of the India–UK tax treaty, could also affect how similar provisions in other tax treaties are applied. A Division Bench of Justices G.S....
Husband's Income Tax Returns Are Personal Information, Not Disclosable Under RTI Act: Delhi High Court
The Delhi High Court has held that a husband's income tax returns constitute “personal information” and are exempt from disclosure under the Right to Information (RTI) Act unless a larger public interest justifies such disclosure. The court set aside a Central Information Commission (CIC) order directing their disclosure to his wife in a matrimonial dispute. Justice Purushaindra Kumar Kaurav ruled that income-related details sought by the wife did not fall within the “larger public interest”...
Deductions For Captive Power Profits Cannot Reduce Export Profit Deduction When Businesses Are Separate: Calcutta HC
The Calcutta High Court has ruled that deductions claimed on profits from captive power generation and export businesses must be computed independently and cannot be reduced against each other where the incomes arise from distinct sources. “The deduction granted under Section 80-IA cannot be reduced while computing profits eligible for deduction under Section 80HHC where the deductions arise from independent businesses,” the court held. A division bench of Justice Rajarshi Bharadwaj and...