
Timely Generated GST Show Cause Notice Uploaded After Deadline Is Time-Barred: Delhi High Court
Kapil Dhyani
27 Oct 2026 5:34 PM IST
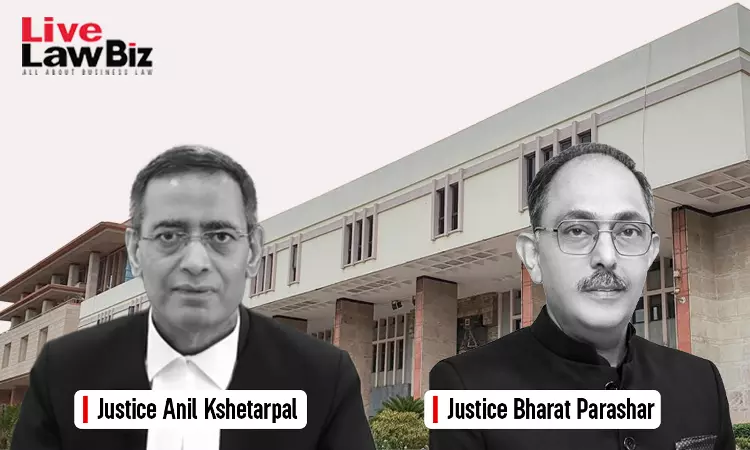
The Delhi High Court has quashed a GST show-cause notice and the consequential demand order against a Hyundai car dealership, holding that a notice generated within the prescribed time but uploaded on the GST portal after the statutory deadline is time-barred.
The division bench of Justices Anil Kshetarpal and Bharat Parashar held that an internally generated notice that remains unconfirmed on the GST system and is not communicated to the taxpayer cannot be treated as validly issued under the Central Goods and Services Tax (CGST) Act, 2017.
The Court was hearing a petition filed by Sikka Motors Pvt. Ltd., challenging a show-cause notice dated May 30, 2024, which was uploaded on the GST portal on August 8, 2024, as well as the demand order dated August 23, 2024.
The dispute arose from scrutiny of the company's GST returns for the financial year 2019-20.
Department alleged that the dealership had wrongly availed input tax credit of ₹10,57,392 from suppliers whose registrations had been cancelled retrospectively and ₹5,57,720 from suppliers who had not filed their GSTR-3B returns.
The company argued that even after accounting for the extended limitation period under CBIC Notification, the show-cause notice was required to be issued by May 31, 2024. Since it was made available on the GST portal only on August 8, 2024, the notice was beyond limitation.
Department on the other hand contended that the notice had been generated and uploaded on the AIO system on May 30, 2024, within the prescribed period. However, due to a technical glitch during migration from the AIO system to the GST BO portal, it could not be integrated with the GST Network (GSTN) and was subsequently uploaded on August 8, 2024.
Rejecting the department's contention, the High Court held that the statutory timeline for issuing a show-cause notice under Section 73(2) of the CGST Act must be read with Section 169, which prescribes the modes of service of notices.
The Court noted that the relevant portal entry showed the notice as “awaiting GSTN confirmation” and did not contain a Common Reference Number (CRN). This indicated that the notice had not been integrated with the common portal or communicated to the taxpayer.
“A notice that remains on an internal system, unconfirmed and without a CRN, cannot be said to have been issued in the eyes of law,” the Court observed.
It added, “The remark appended to the reuploaded notice, or its date of generation, cannot confer retrospective effect on it, as no statutory provision empowers the proper officer to extend the limit under Section 73(2).”
The Court also rejected the department's reliance on the technical glitch, observing that the authorities had made no attempt to serve the notice through alternative modes, such as registered post, speed post or email, despite being aware of the technical issue.
It observed that the consequences of administrative lapses could not be imposed on the taxpayer, nor could such lapses extend a limitation period fixed by Parliament.
As such, the Court quashed the show-cause notice as well as the demand order.
For Petitioner: Advocates Siddarth Malhotra, Prerak Khurana and Ritika Goel
For Respondents: Advocates Raghuvendra Shukla, SPC along with Anil Devlal, GP, Sampan, Manu Shukla, Nandita and Asra Chandra for R-1. Advocates Pranay Mohan Govil, SSC along with Devnit Chaudhuri and Tenzin Lhamo Bhutia for R-2.