
Karnataka High Court Says Pregnancy Justifies Absence From GST Proceedings, Remands Ex-Parte Order
Manu Sharma
29 Sept 2026 3:34 PM IST
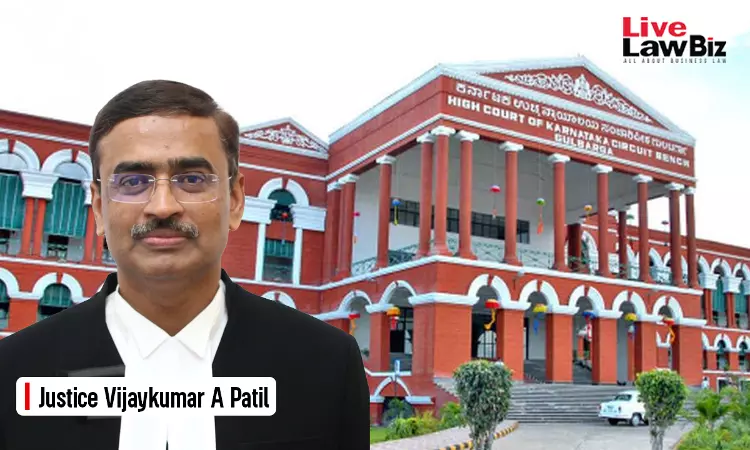
The Karnataka High Court on 18 September held that an ex-parte GST adjudication order can be set aside where a taxpayer's non-appearance is sufficiently justified, including on account of pregnancy and related medical complications.
Justice Vijaykumar A. Patil of the Kalaburagi Bench allowed a writ petition filed by Soumya, proprietrix of Ganga Medical Stores, against the Deputy Commissioner of Commercial Taxes (Audit), Bidar and the Commissioner of Central Tax and Central Excise. The Bench observed:
“The petitioner has offered sufficient explanation for her non-appearance before the authority during the adjudication proceedings.”
An audit notice was issued to the petitioner on 25 July 2025 for FY 2021-22. An intimation of tax demand followed under Section 73(5) of the Central Goods and Services Tax Act, along with a show cause notice dated 24 September 2025. The adjudicating authority subsequently passed an order on 11 December 2025, confirming tax, interest and penalty.
The petitioner submitted that she could not participate in the proceedings due to pregnancy and related medical complications. The order had admittedly been passed ex-parte and that the medical records produced by her supported the explanation for her non-appearance.
The Revenue argued that the petitioner had admitted service of notice and had an alternative statutory remedy under Section 107 of the GST Act.
The Bench, however, relied on the coordinate Bench decision in Sri. Siddappa v. Assistant Commissioner and held that the petitioner deserved an opportunity to submit her reply and supporting documents.
Accordingly, the High Court set aside the adjudication order, subject to the petitioner depositing 10% of the tax demanded by 14 October 2026. It remitted the matter to the adjudicating authority from the stage of submission of the reply and supporting documents.
For the Petitioner: Swati and Rama P.V., Advocates
For the Respondents: Mallikarjun Sahukar, Additional Government Advocate for Respondent No.1 and Girish S. Hulimani, Advocate for Respondent No.2