
GST Appeal Pre-Deposit Has No Impact On ITC Blocking Under Rule 86A Of CGST Rules: Madras High Court
Mehak Dhiman
5 Oct 2026 4:01 PM IST
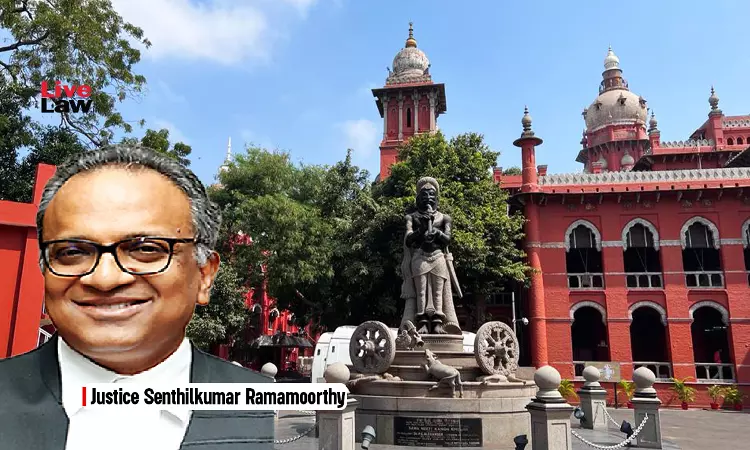
The Madras High Court has held that making the mandatory pre-deposit for filing a GST appeal does not, by itself, require unblocking of Input Tax Credit (ITC) blocked under Rule 86A of the GST Rules.
Justice Senthilkumar Ramamoorthy clarified that although the pre-deposit results in a deemed stay on recovery of the balance demand under Section 107(7) of the Central Goods and Services Tax Act, 2017 (CGST Act), it does not affect a separate blocking order under Rule 86A, and disposed of a petition filed by Syed Ahamed Ibrahim, proprietor of Tvl. Royal Steel Traders, challenging the blocking of Rs. 28,15,364 in his Electronic Credit Ledger. The Bench observed:
“Rule 86A requires that reasons be recorded in support of such order. Being a provisional measure, the life of a blocking order shall not exceed one year,”
The blocked ITC comprised Rs. 14,07,682 under CGST and an equivalent amount under SGST. It was blocked on 7 May 2026 in relation to supplies received from Vasanth Enterprises.
Orders were subsequently passed on 8 June 2026 concerning alleged wrongful availment of ITC. Ibrahim appealed against those orders after making the requisite pre-deposit from his Electronic Cash Ledger. He contended that the deemed stay on recovery under Section 107(7) also required the blocked ITC to be unblocked.
Ibrahim relied on the Madras High Court's decision in Arise Steels Private Limited v. Assistant Commissioner (ST) in support of his contention.
The High Court held that the appeal and the prescribed pre-deposit result in a deemed stay of recovery of the balance demand under Section 107(7). Therefore, no amount could be appropriated towards the stayed demand from either the Electronic Cash Ledger or the blocked Electronic Credit Ledger. However, it clarified:
“Beyond that, the lodging of an appeal and the deemed stay would have no impact on the blocking order under Rule 86A,”
The Bench noted that blocking of ITC under Rule 86A is a provisional measure for which reasons must be recorded and which cannot continue beyond one year. It also noted that the provision permits a taxpayer to seek unblocking.
Since Ibrahim had already submitted a representation dated 17 June 2026 seeking unblocking, the Court directed the authorities to consider it. If the request was accepted, no speaking order would be necessary. If rejected, the authorities were directed to pass a speaking order within one month of receiving the Court's order.
Accordingly, the High Court disposed of the writ petition with no order as to costs.
For the Petitioner: Advocate R. Balachandar.
For the Respondents: Additional Government Pleader (Tax) Amirta Poonkodi Dinakaran.