
Disputes Between Arms Of State, Including Tax Disputes, Should Be Settled Through Consultation: Rajasthan HC
Mehak Dhiman
12 Nov 2026 1:16 PM IST
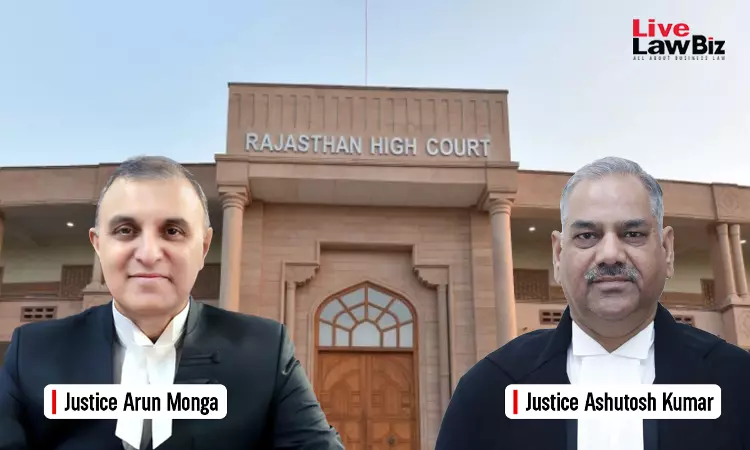
The Rajasthan High Court has observed that disputes between different arms of the state, including the tax dispute before it, should be resolved through consultation rather than coercive proceedings, as litigation ultimately consumes public money.
The court made the observation while referring to a May 22, 2018, office memorandum issued by the Department of Public Enterprises, Ministry of Heavy Industries and Public Enterprises. The memorandum provides a mechanism for resolving commercial disputes involving Central public sector enterprises and government departments.
A Division Bench of Justice Arun Monga and Justice Ashutosh Kumar acknowledged that the memorandum did not strictly cover the present tax dispute between a State authority and a Central tax department. However, it observed that the underlying policy was sound.
"Disputes between arms of the State are better settled across the table than through coercive proceedings. Litigation of this kind consumes public money on both sides. Whatever the outcome, the money stays within the public purse," the court observed.
The Bench suggested that the parties approach the Secretary of the relevant Ministry of the Government of India to explore a resolution, clarifying that this was "an observation, not a direction".
The court made these observations while quashing a GST show cause notice proposing a demand of ₹73.43 crore against the Jaipur Development Authority (JDA).
It also observed that JDA's officers had nothing to gain from evading tax, as any tax payable would merely move from one public fund to another.
"It is difficult to see what the officers of JDA could gain by evading tax payable by JDA. They would gain nothing, directly or indirectly. The tax, if payable, would come out of the funds of JDA. Those are public funds. They would go into the public exchequer. The money would move from one public purse to another," the court observed.
It further remarked:
"If intent to evade is attributed to officers of a State authority who stand to gain nothing, the result would be unsavoury. One government officer would be prosecuting another, without any personal gain attributed or even possible in law. The legislature could not have intended Section 74 to operate in that manner. This consequence reinforces the view we have taken."
The court held that mere non-payment of tax was not enough to establish an intention to evade it. It cautioned that the tax department could not treat Section 74 of the Central Goods and Services Tax (CGST) Act as the default route.
"The Revenue cannot treat Section 74 as the default route and Section 73 as the exception," the court observed, noting that Section 74 carries a longer limitation period, a higher penalty, and the possibility of prosecution.
The notice, issued on September 30, 2025, proposed the demand on road-cutting charges of ₹47.41 crore, additional Floor Area Ratio (FAR) charges and betterment levy of ₹25.86 crore, and sale of Master Plan booklets and application forms worth ₹15.94 lakh.
JDA argued that these receipts arose from its statutory functions and were recorded in its books. The tax department, however, alleged that the authority had failed to disclose and pay its GST liability despite opportunities during the audit.
Rejecting the department's contention that non-payment established an intention to evade tax, the court noted that the receipts were found in JDA's own records during the audit. It held that the notice failed to disclose the essential jurisdictional fact of an intention to evade tax.
The Bench clarified that it was not deciding whether the receipts were actually taxable under GST. It quashed the show cause notice and all proceedings initiated under it.
For Petitioner: Jatin Harjai, Advocate, with Rohan Agarwal and Nikshubha Sharma, Advocates
For Respondent: Bharat Vyas, ASG Senior Advocate, with Nitin Jain Bhandari, Advocate and Kinshuk Jain, Senior Standing Counsel, with Saurabh Jain and Parth Khandal, Advocates