
Time Spent In Writ Petition Not Automatically Excluded From GST Appeal Limitation: Delhi High Court
Kapil Dhyani
15 Oct 2026 7:43 PM IST
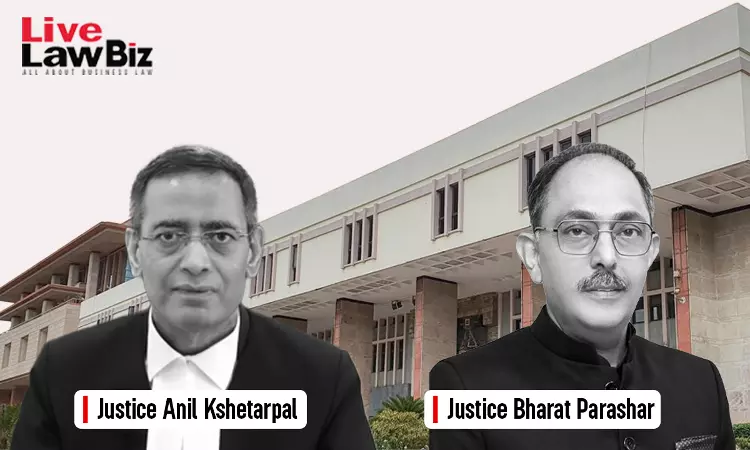
The Delhi High Court has clarified that the time spent pursuing a writ petition cannot be automatically excluded while computing the limitation period for filing a statutory appeal against a GST adjudication order.
The Division Bench of Justices Anil Kshetarpal and Bharat Parashar observed that if an assessee files an application under Section 14 of the Limitation Act, 1963, seeking exclusion of the period during which the writ petition remained pending, the Appellate Authority must consider the application in accordance with law.
The Court clarified that merely filing such an application would not automatically result in the exclusion of the period.
The observation came while the Court was dealing with a challenge to a show-cause notice dated June 30, 2025, an adjudication order dated December 17, 2025, and a subsequent rectification order dated December 30, 2025, in proceedings under the Central Goods and Services Tax Act, 2017. The proceedings related to the financial year 2018–19 and resulted in the imposition of a penalty.
Petitioner contended that he acquired knowledge of the adjudication order only on May 11, 2026, when the relevant particulars became available on the GST portal. He also questioned whether the order had been effectively communicated to him.
The Revenue however submitted that the adjudication order had been sent to Petitioner's registered email address as well as through Speed Post.
The Court left the rival contentions concerning service of the order, the date of communication and computation of limitation open for consideration by the competent Appellate Authority.
On exclusion of time spent in writ proceedings, the Bench observed:
“In the event the Petitioner files an application under Section 14 of the Limitation Act, 1963, seeking exclusion of the period during which the present Writ Petition remained pending, the Appellate Authority shall consider such application in accordance with law. The mere filing of such an application shall not be construed as an automatic exclusion of the said period, and the question shall be determined by the Appellate Authority in the light of the applicable legal principles and the facts placed before it.”
For Petitioner: Advocates A.K. Babbar and B.K. Tripathi, Adv
For Respondents: Prateek Tanwar, SPC, UOI with Khanak Tanwar and Sarthak Rana, Advs. for R1. Monica Benjamin, SSC with Ms. Laiba Arif and Prerika Narang, Advs. for R-2 and R-3