
Delhi High Court Refuses To Quash 80-Page GST Show-Cause Notice In Writ Over Alleged Fake ITC Network
Kapil Dhyani
28 Oct 2026 8:02 PM IST
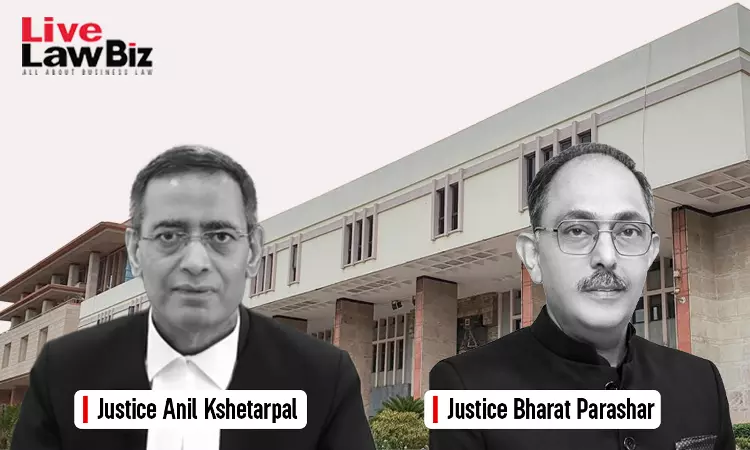
The Delhi High Court has refused to interfere with GST demand orders against a trader accused of availing and passing on ineligible Input Tax Credit (ITC) through invoices allegedly unsupported by genuine supplies of goods, observing that a detailed show-cause notice setting out the alleged transactions and modus operandi did not warrant interference at the writ stage.
The division bench of Justices Anil Kshetarpal and Bharat Pashar relegated the trader to statutory appellate remedy under the Central Goods and Services Tax (CGST) Act, 2017.
The Court was dealing with two petitions filed by Manoj Kumar, proprietor of M K Steel Traders, challenging separate orders dated February 4, 2025, passed by the Additional Commissioner, Central Goods and Services Tax.
The orders raised demands of ₹6.14 lakh and ₹2.93 crore, respectively, in proceedings arising from an investigation into the alleged availment and passing on of ineligible ITC through invoices that did not correspond to genuine supplies of goods.
According to the Department, the investigation concerned a network of firms allegedly created to facilitate the passing on of ineligible ITC. The show-cause notices referred to a search at the premises of one Mohit Jain, during which stamps, letterheads and invoices pertaining to multiple firms were allegedly seized.
The Department alleged that the transactions reflected in the invoices did not correspond to actual receipt or supply of goods and formed part of an arrangement to defraud the revenue.
One of the trader's principal objections was that the show-cause notice invoking Section 74 of the CGST Act did not disclose sufficient particulars to justify the initiation of proceedings for alleged fraud, wilful misstatement or suppression of facts.
The Court however noted that the show-cause notice in one of the petitions ran into nearly 80 pages and contained a detailed account of the alleged transactions, the involvement of multiple firms and the manner in which invoices unsupported by genuine supplies were allegedly used to avail and pass on ineligible ITC.
It observed that the fact that the notice was common to several noticees did not by itself render it deficient. It added that the trader's contention that the notice omitted vital particulars was also not in itself sufficient to warrant interference with the impugned order in writ jurisdiction.
The Court clarified that the trader remained free to challenge the Department's allegations, the material relied upon and the conclusions reached by the adjudicating authority before the statutory appellate forum.
The Court also considered the Supreme Court's judgment in M/s G.R. Infra Projects Limited v. State of Madhya Pradesh, which held that merely using expressions such as “fraud”, “wilful misstatement” or “suppression of facts”, without disclosing the factual particulars supporting such conclusions, would not be sufficient to sustain proceedings under Section 74.
It reiterated that the factual basis for invoking Section 74 must be discernible from the show-cause notice itself. However, it found that the judgment did not furnish sufficient grounds to bypass the statutory appellate remedy in the present cases, having regard to the contents of the notices and the objections raised.
In the second petition, the trader separately contended that the show-cause notice had not proposed the imposition of a penalty, although the final order directed him to pay one.
The Court declined to decide the issue at the writ stage, observing that the statutory appellate authority was competent to examine whether the notice contained an adequate proposal to sustain the penalty.
For Petitioner: Advocates A.K. Babbar, B.K. Tripathi and Ankur Sethi
For Respondents: Akash Verma, SSC.