Delhi High Court Dismisses Customs Department's Appeals Against ₹175 Crore CVD Refund To Micromax
Kapil Dhyani
2 Nov 2026 6:37 PM IST
The Delhi High Court has dismissed five appeals filed by the Customs Department challenging the sanction of customs duty refunds to Micromax Informatics Limited, holding that the company had successfully established that it had not passed on the burden of countervailing duty (CVD) to its customers.
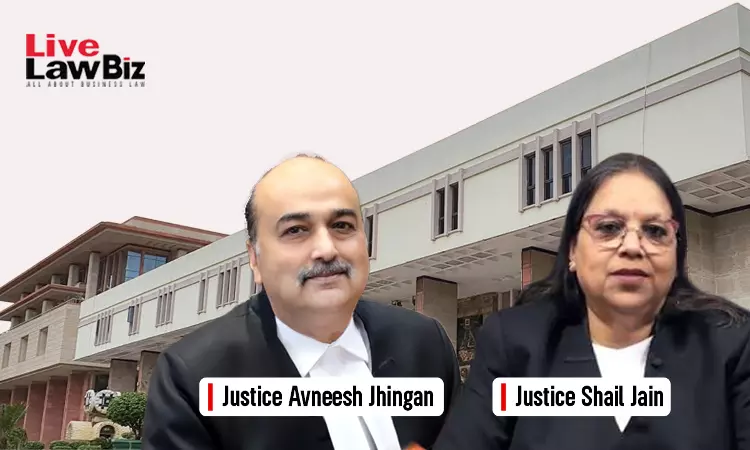
The Division Bench of Justices Avneesh Jhingan and Shail Jain upheld the findings of the Commissioner of Customs (Appeals) and CESTAT, which had ruled in favour of Micromax.
The Court held that the findings of the Tribunal suffered from no legal or factual error, much less perversity, and that no substantial question of law arose for consideration.
The five appeals concerned customs duty refunds amounting to approximately ₹175 crore, along with interest, for the period between June 2014 and March 2015.
For context, Micromax had imported cellular phones and mobile parts during the relevant period and paid CVD on the imported goods.
Following the Supreme Court's decision in SRF Ltd. v. Commissioner of Customs, Chennai, which held that CVD was not payable on the goods in question, Micromax applied for refunds of the duty paid.
The refund claims were initially sanctioned, but the amounts were directed to be credited to the Consumer Welfare Fund under Section 27(2) of the Customs Act, 1962, on the ground that Micromax had passed on the burden of duty to consumers.
Micromax challenged the decision before the Commissioner of Customs (Appeals), which held that the adjudicating authority had ignored the certificate issued by an independent chartered accountant, the statutory auditor's certification of the company's balance sheets, and other relevant documents.
The appellate authority concluded that the burden of CVD had not been passed on to customers and directed that the refund amounts be paid to Micromax.
The Customs Department challenged the decision before CESTAT, which dismissed the appeals.
The Department thereafter approached the High Court, contending that the chartered accountant's certificate was insufficient to establish that the burden of duty had not been passed on to consumers.
It also argued that Micromax had not shown the refund amounts as receivables in its balance sheets and that the uniformity of prices before and after the change in CVD payment did not establish that the burden had not been passed on.
The High Court noted that the undisputed position was that no CVD was payable on the goods imported by Micromax during the relevant period.
The only issue was whether Micromax had passed on the burden of CVD to its customers and whether it had successfully rebutted the presumption under Section 28D of the Customs Act that the incidence of duty had been passed on to consumers.
The Court observed that Micromax had produced invoices, balance sheets for the relevant financial years, and a certificate issued by a chartered accountant certifying that the burden of CVD had not been passed on to customers.
The Tribunal had considered these documents and upheld the factual finding that the invoices showed that CVD was neither recovered from buyers nor reflected in the invoices.
The Court further noted that the rejection of the chartered accountant's certificate by the adjudicating authority was contrary to Board Circular No. 18/2010 dated August 7, 2010.
It observed that the Commissioner's reliance on the certificate, which stated that the incidence of CVD had not been passed on, was in consonance with the circular.
The Court also relied on its decision in Principal Commissioner of Customs (ACC Imports) v. Nokia India Sales Pvt. Ltd., which held that a chartered accountant's certificate could not be ignored, particularly when supported by other documents such as books of account.
As such, it held that the Tribunal's conclusion suffered from no legal or factual error and dismissed all appeals.
For Appellant: Advocate Aditya Singla, SSC
For Respondent: Senior Advocate Balbir Singh, Advocates Pranav Sarthi, Ayush Raj, Disha, Vedant Kohli, Vinayak, Prachi Dhingra, Utkarsh Vatsa and Udit Bajpai.