Customs Can Examine Third-Party Payments To Verify Exporters' Duty Drawback Claims: Delhi High Court
Kapil Dhyani
5 Nov 2026 12:32 PM IST
The Delhi High Court has held that Customs authorities can examine whether payments received from third parties actually represent sale proceeds for exported goods while determining an exporter's entitlement to retain duty drawback.
Referring to Section 75 of the Customs Act, 1962, which provides for duty drawback on exported goods, the court ruled,
"The reference in Section 75 to “sale proceeds in respect of such goods” necessarily requires the Customs authorities, when the entitlement to drawback is put in issue, to examine whether the amounts relied upon as export realisations have the requisite nexus with the exports in question. The Customs authorities are not thereby exercising the regulatory jurisdiction of the Reserve Bank of India under FEMA. They are examining the statutory entitlement to retain a benefit granted under the Customs Act,"
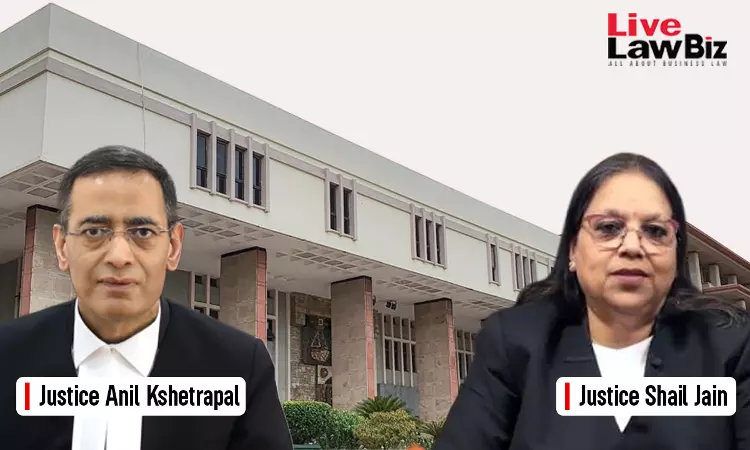
The Division Bench of Justices Anil Kshetarpal and Shail Jain held that the mere fact that money had been credited to an exporter's account did not establish that it was genuine sale proceeds for the goods against which drawback had been claimed.
"Receipt of money in a bank account is a fact; whether that receipt constitutes sale proceeds in respect of the exported goods is a matter which has to be determined from the surrounding circumstances and the evidence available on record"
The court, however, clarified that third-party remittances are not invalid in every case.
The development comes in a batch of 22 Customs appeals, whereby the Court set aside CESTAT order and restored the Commissioner of Customs' adjudication, except for the penalty imposed on Nitin Gupta of Oak Shipping Services Pvt. Ltd., which remained set aside.
The proceedings arose from exports of readymade garments by five firms to the UAE between 2008–09 and March 2014. The exporters claimed a drawback under Section 75 of the Customs Act and benefits under the Focus Product Scheme and Focus Market Scheme.
The Directorate of Revenue Intelligence alleged that the goods had been overvalued to obtain higher export incentives and that remittances shown as export proceeds came from third parties rather than the declared overseas buyers. The investigation also alleged that the remittances formed part of a wider arrangement involving movement of funds through different accounts.
The adjudicating authority confirmed recovery in respect of consignments linked to 1,650 Bank Realisation Certificates (BRCs) cancelled by Punjab National Bank. It dropped the proposals concerning other consignments for want of sufficient evidence. CESTAT subsequently set aside the demands.
The Court held that Section 75 reference to “sale proceeds in respect of such goods” requires Customs, when drawback entitlement is disputed, to examine whether the amounts shown as export realisations have the necessary connection with the goods exported.
It rejected the exporters' contention that this enquiry fell exclusively within the Reserve Bank of India's domain under the foreign-exchange framework. The Court said Customs was not exercising the RBI's regulatory jurisdiction under FEMA; it was examining whether the exporter was entitled to retain a benefit granted under the Customs Act.
The Court emphasised that the Revenue's case was not based merely on the fact that the remitter was someone other than the named buyer. The material relied upon included the identity and business activities of the remitters, their relationship with the declared buyers, the movement of funds, overseas enquiries and documents concerning the corresponding imports.
The Court said the CESTAT had treated the dispute as one concerning the validity of foreign-exchange transactions, whereas the issue was whether the amounts received could be treated as genuine sale proceeds for the exported goods.
Overvaluation allegation did not bar appeals under Section 130
The exporters argued that the appeals were not maintainable under Section 130 because the case involved valuation of goods, while their assessable value had not been redetermined under Section 14 of the Customs Act read with the Customs Valuation (Determination of Value of Export Goods) Rules, 2007.
The Court rejected the objection, holding that the Section 130 exclusion applies where the question of value is connected with assessment. Here, the alleged overvaluation was relied upon as evidence of fraudulent availment of export benefits, not as a request to determine the goods' assessable value.
It observed that the absence of a fresh valuation exercise under Section 14 and the 2007 Rules did not, by itself, make the investigation material irrelevant to the allegation of deliberate misdeclaration. Whether that material was sufficient to establish fraudulent availment was a matter to be assessed on the evidentiary record.
The exporters also relied on a civil court decree declaring the cancellation of the BRCs null and void.
The Court however held that the decree did not, merely by its existence, conclusively determine the Customs Department's independent statutory rights because Customs was not a party to the civil proceedings and was not shown to be claiming through either party.
The Court said the decree had to be considered alongside the material relied upon in the adjudication proceedings and CESTAT erred in treating it as having, by itself, extinguished the basis of the Revenue's case.
Section 28AAA: Separate proceedings against scrip users not a precondition
The Court also held that Section 28AAA contains specific statutory requirements and that a mere allegation of fraud would not be enough to recover duty foregone on imports made against duty-credit scrips.
However, it found that CESTAT had erred in treating the absence of separate proceedings against subsequent users of the scrips, or the absence of independent invalidation of the scrips, as determinative. The relevant question was whether the ingredients of Section 28AAA were established against the concerned noticees on the evidence and allegations in the show-cause notices.
The Court said liability under the provision could not be made dependent on separate proceedings against every subsequent user unless the statute itself made such proceedings a condition precedent.
While concluding, the Court upheld the setting aside of the penalty imposed on Nitin Gupta, a director of Oak Shipping Services Pvt. Ltd. It found that the required procedural safeguards, including notice, supply of relevant documents and an opportunity of hearing had not been complied with.
The Court therefore allowed the Revenue's appeals, set aside CESTAT's common order and restored the Commissioner's adjudication order in all other respects, while keeping Gupta's penalty set aside.
For Appellant: Advocates Anurag Ojha, SSC along with Dipak Raj, Aryaman Singh Chouhan and Aditya Chaudhary.
For Respondent: Senior Advocate Tarun Gulati along with Advocates Dr. G. K. Sarkar, Malabika Sarkar, Prashant Srivastav, Shruti Kulkarni and Karan Khaitan