
Starch Used In Liquid Glucose Production Qualifies For DFIA Benefits Under SION: Gujarat High Court
Arvind Kumar Tiwari
27 Oct 2026 4:30 PM IST
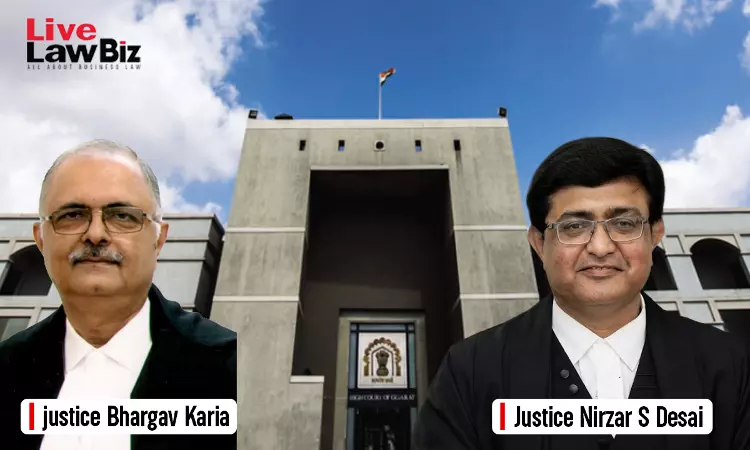
The Gujarat High Court on 21 October held that starch used as an immediate input in manufacturing liquid glucose concentrate qualifies for duty-free import benefits under the Duty Free Import Authorisation (DFIA) Scheme when classified under Standard Input Output Norms (SION) Entry E22, rather than E76, which specifies maize.
A Division Bench comprising Justices Bhargav D. Karia and Nirzar S. Desai dismissed the Revenue Department's appeal against the Customs, Excise and Service Tax Appellate Tribunal (CESTAT) order in favour of Sanstar Bio Polymers Ltd., holding that Customs authorities could not invoke Sections 113(i) and 114(iii) of the Customs Act, 1962, without wilful misstatement or suppression of facts in obtaining the DFIA authorisations. It observed:
“Therefore, the CESTAT has rightly concluded that the correct SION Entry is E22 and since starch slurry is used as an immediate input by the assessee in manufacturing of the export item i.e. liquid concentrate, it cannot be said that starch was not an input for the export item.”
The dispute arose from Sanstar Bio Polymers' exports of food-grade liquid glucose concentrate between February 2015 and July 2016. The company claimed DFIA benefits by declaring maize (corn) starch as an input under SION Entry E22. Based on the export shipping bills, the Directorate General of Foreign Trade (DGFT) issued seven DFIA authorisations, which were subsequently transferred to third parties for duty-free imports.
Following an investigation, the Directorate of Revenue Intelligence alleged that the company had incorrectly classified the input to obtain the benefits. The department contended that raw maize fell under SION Entry E76, while E22 specified starch.
The investigation found that the company processed maize into starch slurry, a portion of which was directly used to manufacture liquid glucose, while the remaining portion was dried into powdered maize starch. The department alleged that powdered starch was not used in manufacturing liquid glucose and questioned the company's eligibility for benefits under E22.
The department issued a show-cause notice proposing recovery of approximately Rs. 4.09 crore in customs duty under Section 28AAA of the Customs Act, along with confiscation under Section 113(i) and penalties under Section 114(iii). The adjudicating authority confirmed the demand, ordered confiscation and imposed penalties.
Subsequently, the CESTAT set aside the order, finding that starch slurry was the immediate input used to manufacture liquid glucose concentrate and that the company had correctly claimed benefits under E22.
Before the High Court, the Revenue argued that the applicable exemption notifications and Foreign Trade Policy required the inputs declared in the shipping bills to correspond to the materials actually used in the export product. It contended that the company had declared powdered maize starch to obtain DFIA benefits even though starch slurry was directly used in manufacturing liquid glucose.
The Court identified the correct classification under the competing SION entries as the central issue. It noted that liquid glucose concentrate was manufactured using starch slurry, which was essentially starch in slurry form, and that starch was a necessary input in the manufacturing process.
It also observed that E22 covered liquid glucose in both liquid concentrate and powder forms, whereas E76 covered liquid glucose in liquid form. The Court held that the use of starch slurry as the immediate input supported classification under E22.
Further, the Bench noted that the DGFT-issued DFIA authorisations remained valid and had neither been cancelled nor suspended. It held that the Revenue could not invoke Section 28AAA in the circumstances, particularly when the DGFT had accepted the classification under E22 and had not initiated proceedings to cancel or suspend the authorisations. It added:
“The CESTAT has, therefore, rightly come to the conclusion that the assessee has rightly classified its product under SION Entry E22. In such circumstances, the Revenue authorities were not justified in invoking the provisions of Section 113(i) read with Section 114(iii) of the Act, in view of the findings of fact recorded by the CESTAT that there was no willful misstatement or suppression of facts for obtaining the DFIA authorizations regarding inputs which were classified under SION Entry E22 by the assessee.”
Accordingly, the High Court dismissed the Revenue Department's appeal, finding no substantial question of law, and upheld CESTAT's order setting aside the customs duty demand, confiscation and penalties.
Counsel for Appellant: Hetvi H. Sancheti, Senior Standing Counsel