
CUSTOM&EXCISE&SERVICE TAX
Calcutta High Court To Examine If Customs Can Treat 'Obscene Adult Sex Toys' As Prohibited Goods
The Calcutta High Court is set to examine whether goods described as “obscene adult sex toys” can be treated as “prohibited goods” under the Customs Act without identifying a specific statutory or notification-based prohibition. Justice Smita Das De is hearing a petition filed by Pracha Aalloy Private Limited against a July 22, 2026, Customs order. The key question is whether describing the goods as “obscene adult sex toys” and invoking Section 292 of the Indian Penal Code, 1860 can, by...
Conditions Of All Exemption Notifications Must Be Strictly Complied With For Simultaneous Benefit: CESTAT Delhi
The Delhi bench of the Customs, Excise and Service Tax Appellate Tribunal (CESTAT) has held that an importer claiming exemptions under multiple customs notifications must comply with the conditions prescribed under each notification.The tribunal observed that “strict interpretation to all notifications has simultaneously to be given”, and that the conditions of all the notifications have to be strictly complied with to avail their simultaneous benefit.A bench comprising Officiating President Dr....

Written Acceptance Of Enhanced Customs Value Does Not Bar Statutory Appeal: CESTAT Allahabad
The Customs, Excise & Service Tax Appellate Tribunal (CESTAT), Allahabad, has reiterated that an importer's written acceptance of an enhanced assessable value does not, by itself, prevent the importer from challenging the reassessment in appeal.Relying on the Delhi High court's ruling in Niraj Silk Mills v. Commissioner of Customs (ICD), Patparganj, the tribunal held that accepting a reassessment and giving up a speaking order are not the same as giving up the statutory right to challenge...
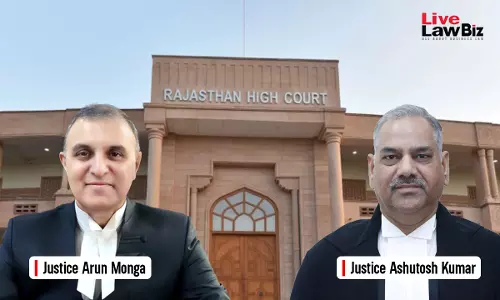
No Customs Interest On Capital Goods Kept In Bonded Warehouse Until Clearance: Rajasthan High Court
The Rajasthan High Court has upheld the setting aside of a ₹2.88-crore customs interest demand on solar modules imported by Acme Aklera Power Technology Pvt. Ltd. It held that interest under Section 61(2) of the Customs Act cannot be charged on capital goods covered by Section 61(1)(a). A Division Bench comprising Justice Arun Monga and Justice Ashutosh Kumar held that such capital goods can remain in a warehouse until clearance if they are intended for use in a warehouse where manufacture or...
Declared Goods Used To Conceal Undeclared Imports Can Be Confiscated: CESTAT Allahabad
The Customs, Excise & Service Tax Appellate Tribunal (CESTAT), Allahabad, has ruled that declared goods can also be confiscated when they are used to conceal large quantities of undeclared goods.“It is not in dispute that the goods imported by the appellant was accompanied and used for concealment of large quantities of undeclared goods sought to be smuggled in to India by violating the provisions of Trade Markets and Intellectual Property Laws,” Technical Member Sanjiv Srivastava observed....

CENVAT Credit Available On Depot Clearing And Forwarding Services: CESTAT Hyderabad
The Hyderabad bench of the Customs, Excise and Service Tax Appellate Tribunal (CESTAT) has held that CENVAT credit is admissible on clearing and forwarding services provided at an assessee's depots. This includes receipt, unloading, storage, handling and loading of cement at depots from where the goods were subsequently sold.The tribunal observed, “Such services have a direct nexus with the appellant's business of manufacture and sale of cement and are eligible input services.” It held that...
Meter Testing Naturally Bundled With Electricity Distribution, Not Taxable Separately: CESTAT Hyderabad
The Customs, Excise and Service Tax Appellate Tribunal (CESTAT), Hyderabad, has ruled that meter-testing charges collected by an electricity distribution utility are naturally bundled with distribution of electricity and cannot be taxed separately. “We accordingly hold that meter-testing is ancillary and naturally bundled element of distribution of electricity. The activity takes its tax character from the principal service falling within Section 66D(k) of the Finance Act, 1994,” Judicial Member...

2016 Amendment To CENVAT Credit Reversal Formula Clarificatory, Applies Retrospectively: CESTAT Allahabad
The Customs, Excise & Service Tax Appellate Tribunal, Allahabad on Thursday held that the 2016 amendment to the CENVAT credit reversal formula under Rule 6(3A) was clarificatory in nature. The amendment clarified that, for calculating the credit to be proportionately reversed, credit used exclusively for taxable services or dutiable goods is not to be included; only common CENVAT credit is relevant.The court observed that Notification No. 13/2016-CE (NT) dated March 1, 2016 substituted the...
CESTAT Chennai Upholds Toyota's Classification Of Nine Imported Sensors, Sets Aside Reclassification
The Chennai Bench of the Customs, Excise and Service Tax Appellate Tribunal (CESTAT) has upheld Toyota Kirloskar Motors Pvt. Ltd.'s classification of nine imported sensors as thermistors, gas-analysis apparatus, measuring or checking instruments, motor-vehicle parts and electrical apparatus.“The goods have to be classified in the condition in which they are imported, having regard to their objective characteristics and function,” the tribunal observed. It also held that where the Revenue seeks...

Authorised Courier Not Liable For Export Of Prohibited Goods Without Proof Of Knowledge: CESTAT Chennai
The Chennai Bench of the Customs, Excise and Service Tax Appellate Tribunal (CESTAT) on 9 September held that an authorised courier cannot be penalised merely because prohibited goods are found concealed in an export consignment, unless the Revenue establishes the courier's knowledge, participation or a specific act or omission connecting it with the attempted improper export. A Division Bench comprising Judicial Member P. Dinesha and Technical Member M. Ajit Kumar allowed an appeal filed by...
Telangana High Court Upholds Gimpex's Target Plus Duty Exemption, Says Broad Nexus Sufficient
The Telangana High Court on 11 August upheld the relief granted to Gimpex Limited, holding that the extended period of limitation could not be invoked in the absence of material showing fraud, wilful misstatement or suppression of facts with an intent to evade duty. A Division Bench comprising Justices P. Sam Koshy and Narsing Rao Nandikonda observed that a strict product-to-product nexus between imported and exported goods was not required to claim duty exemption under the Target Plus Scheme....
Govt Can't Continue Proceedings For Statutory Dues Omitted From Approved Resolution Plan: CESTAT Chennai
The Chennai Bench of the Customs, Excise and Service Tax Appellate Tribunal (CESTAT) on 7 September held that statutory dues owed to the Central Government, State Government or local authority, which are not included in a resolution plan approved by the National Company Law Tribunal (NCLT), stand extinguished and proceedings concerning such dues cannot be continued. A Division Bench comprising Judicial Member Ajayan T.V. and Technical Member Vasa Seshagiri Rao was dealing with a customs appeal...